
Irrevocable Life Insurance Trust (ILIT): How It Works, Pros, Cons & Who It Fits
An irrevocable life insurance trust, usually called an ILIT, is an advanced estate-planning tool that can hold a life insurance policy outside of your taxable estate while also giving you more control over how the proceeds are handled for beneficiaries.
That is why this page matters. Most people are not just asking what an ILIT is. They are asking whether it is worth the complexity, whether it helps with estate tax exposure, how much control they give up, and when a trust is smarter than naming beneficiaries directly.
The real question is not just what an irrevocable life insurance trust is. The real question is whether the tradeoff of less control is worth the estate-planning, liquidity, and beneficiary-management benefits in your situation.
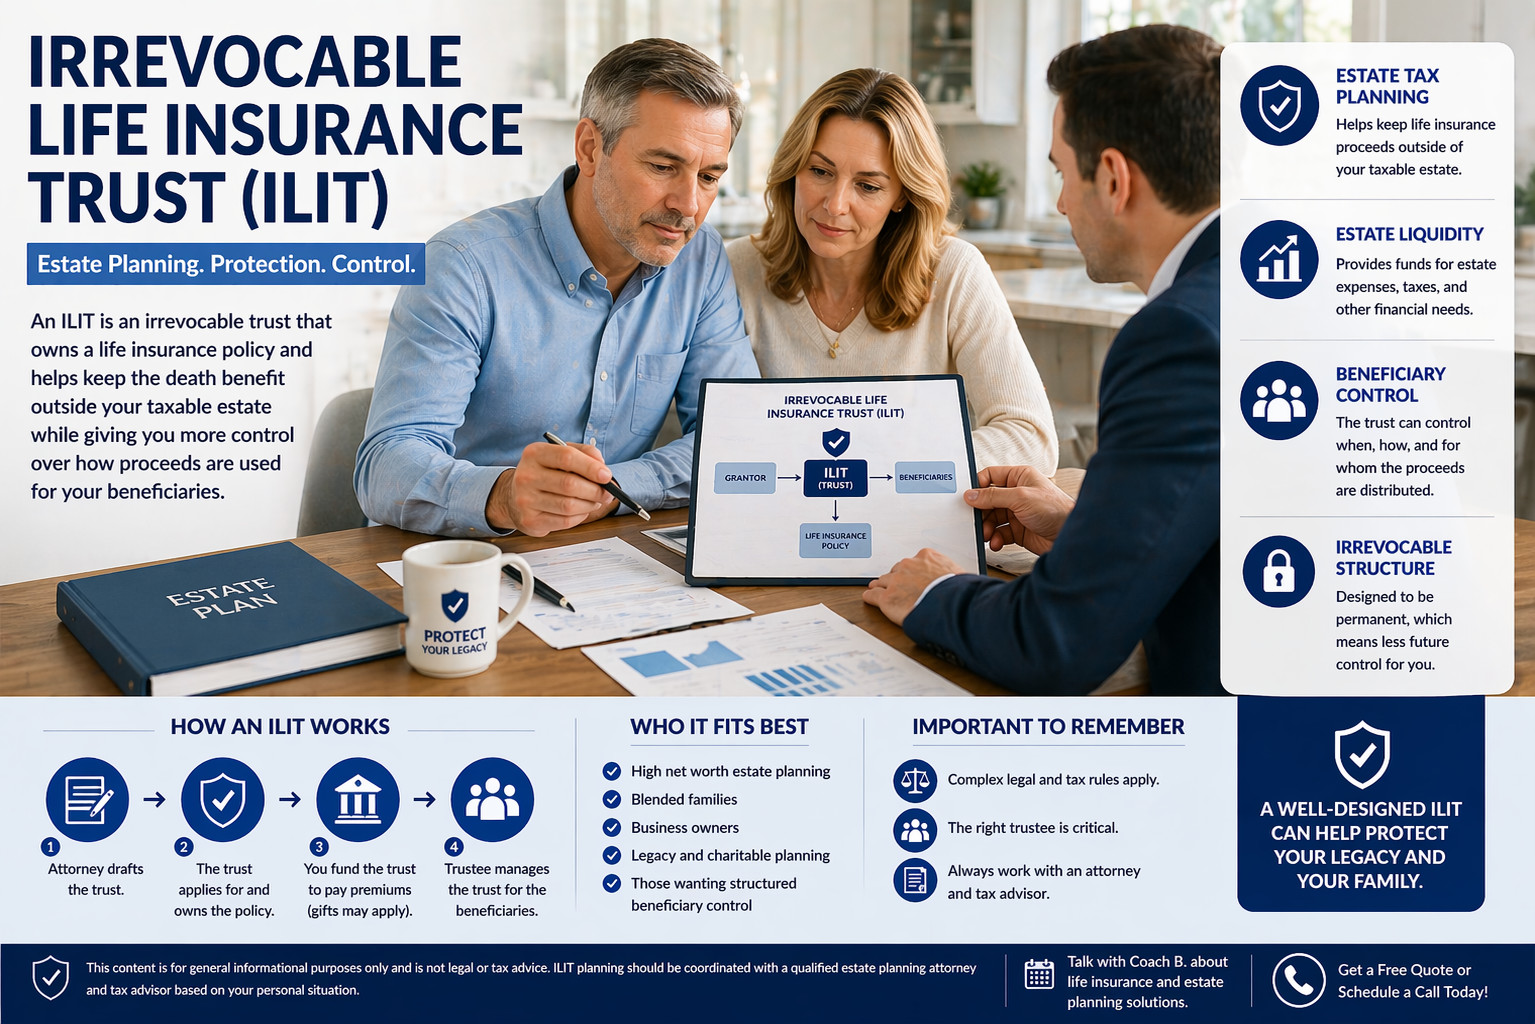
- An ILIT is an irrevocable trust that owns a life insurance policy.
- It is commonly used to help keep policy proceeds outside the taxable estate.
- It can also help with beneficiary control and estate liquidity planning.
- The big tradeoff is that you usually give up meaningful future control once it is set up properly.
- This is usually an attorney-and-CPA topic, not a do-it-yourself life insurance move.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on product fit, underwriting, clarity, and usefulness — not pressure.
Important: This page is general educational information, not legal or tax advice. ILIT design should be handled with an estate-planning attorney and coordinated with your CPA or tax advisor.
Editorial note: ILIT pages often get written too loosely. The core truth is simple: an ILIT can create real planning advantages, but those advantages usually come from giving up future control and structuring ownership correctly from the start.
What an ILIT Usually Is in Plain English
An ILIT is an irrevocable trust created to own a life insurance policy. Instead of you owning the policy directly, the trust owns it. The trust terms can then control how the death benefit is managed and distributed when the insured person dies.
Trust owns the policy
The policy is owned by the trust rather than by the insured individual personally.
Irrevocable structure
The setup is meant to be permanent, which is why control is much tighter than with revocable planning tools.
Beneficiary instructions
The trust can direct how and when proceeds are used or distributed for beneficiaries.
Advanced planning tool
This is usually a higher-level estate-planning move, not a basic beneficiary designation question.
Why People Use an Irrevocable Life Insurance Trust
Estate-tax planning
A common goal is helping keep the death benefit outside the taxable estate when the trust is structured correctly.
Estate liquidity
The trust can help create liquidity so heirs or the estate are not forced to sell assets quickly at the wrong time.
Beneficiary control
Some families want more structure than a direct lump-sum payout to an individual beneficiary.
Complex family planning
ILITs can be useful when there are blended-family concerns, spendthrift concerns, or long-term distribution goals.
The Biggest Tradeoff: Control
| Planning Feature | Why It Can Help | What You Give Up |
|---|---|---|
| Irrevocable ownership | Can support estate-planning goals | You generally do not keep full future control the way you would with directly owned assets |
| Trust-based beneficiary control | Can create rules around distribution timing and use | You are relying on the trust design and trustee rather than simple personal ownership |
| Separate trust structure | Can improve planning clarity and administration | It adds legal setup, ongoing administration, and coordination work |
| Estate-planning efficiency | Can be valuable in the right estate context | May be unnecessary complexity for households that do not need advanced trust planning |
The biggest ILIT mistake is acting like you still control everything the same way after the trust is in place. Usually, that is exactly what the structure is designed to change.
How an ILIT Usually Works
Step 1: attorney drafts the trust
The trust document is created first so ownership, trustee powers, and beneficiary rules are handled correctly.
Step 2: the trust owns the policy
The trust is then set up to own a new policy or, in some cases, to hold an existing one as part of a broader legal plan.
Step 3: trustee administers the trust
The trustee manages the trust according to the document and helps carry out the trust’s distribution rules later.
ILIT vs Naming a Beneficiary Directly
| Approach | Main Strength | Main Limitation |
|---|---|---|
| Name beneficiaries directly | Simple, fast, and easy for ordinary situations | Less control over how proceeds are used after payout |
| Use an ILIT | Can improve beneficiary control and estate-planning structure | More legal complexity, more administration, and less future flexibility |
For many households, direct beneficiaries are enough. ILITs make the most sense when the family is trying to solve a more advanced planning problem than a simple death-benefit payout.
Who an ILIT Usually Fits Best
Good fit if…
- you are doing genuine estate-tax or estate-liquidity planning
- you want structured beneficiary control instead of a direct payout
- you have a blended family or more complex family distribution goals
- you are already working with estate-planning counsel
Usually not the best fit if…
- you are mainly shopping for basic family protection
- you want full ongoing control with easy future changes
- your estate-planning needs are simple
- you do not want ongoing legal and administrative complexity
Main Pros and Cons of an Irrevocable Life Insurance Trust
Pros
- can support estate-tax planning in the right situation
- can create estate liquidity without forcing asset sales
- can provide more control over when and how beneficiaries receive funds
- can be useful in complex family or legacy-planning situations
Cons
- it is usually much harder to change once it is established
- you generally give up meaningful control
- it adds legal, tax, and trustee coordination work
- it may be unnecessary for families with simpler planning needs
How Coach B Would Shop This
Step 1: define the real planning problem
Are we solving estate tax, estate liquidity, beneficiary control, or all three? The trust should match the real job.
Step 2: coordinate the trust before the policy
This is not usually a “buy the policy first and figure out the trust later” topic. Ownership planning matters early.
Step 3: keep attorney and tax counsel involved
The insurance product is only one part of the solution. The legal structure is what makes the planning work.
The Bottom Line
An irrevocable life insurance trust can be a powerful estate-planning tool when the goal is more than just leaving a death benefit behind. In the right situation, it can help with estate-tax planning, liquidity, and beneficiary control.
But the planning advantages usually come from structure and sacrifice. The “irrevocable” part is the point. If you want flexibility and easy future changes, this is usually not the right tool. If you need advanced planning, it can be a very smart one.
Helpful Related Pages
Whole Life Insurance
Best next page if you are still deciding which kind of permanent life insurance policy would even be appropriate for advanced planning.
Explore Whole Life →Universal Life Insurance
Best next page if you are comparing other permanent-policy designs used in legacy or estate planning conversations.
Explore Universal Life →Life Insurance Rates
Best next page if you want the broader pricing context before drilling into advanced ownership planning.
See Life Insurance Rates →Life Insurance Calculator
Best next page if you still need to estimate how much coverage should be in the planning conversation in the first place.
Use the Calculator →Frequently Asked Questions
What is an irrevocable life insurance trust?
An ILIT is an irrevocable trust designed to own a life insurance policy and control how the proceeds are handled for estate-planning and beneficiary purposes.
Why do people use an ILIT?
People usually use ILITs for estate-tax planning, estate liquidity, and more structured beneficiary control in complex family or legacy situations.
Can I still control the policy after I put it in an ILIT?
Usually not in the same way you could if you owned it directly. The planning benefits normally come with meaningful limits on future control.
Is an ILIT right for everyone?
No. It is generally a more advanced estate-planning tool and is often unnecessary for families with simpler beneficiary and estate needs.
Should I set up an ILIT without an attorney?
Usually no. Because ILITs are legal and tax-sensitive structures, they should normally be designed with estate-planning counsel and coordinated with tax advice.


