
Life Insurance Classifications Explained: Preferred Plus vs Standard, Table Ratings & How to Qualify
Life insurance classifications are the risk buckets insurers use to decide how much you pay. Better health and lower risk usually mean better rate classes and lower premiums.
This guide explains what life insurance classifications mean, how companies decide your rate class, what “table rated” really means, and what you can do to improve your chances of getting a better offer.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent (Coach B. Insurance)
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on fit, underwriting, and clarity — not pressure.
Editorial note: This page is educational. Classification names, underwriting rules, and how companies weigh risk factors can vary by insurer and state.
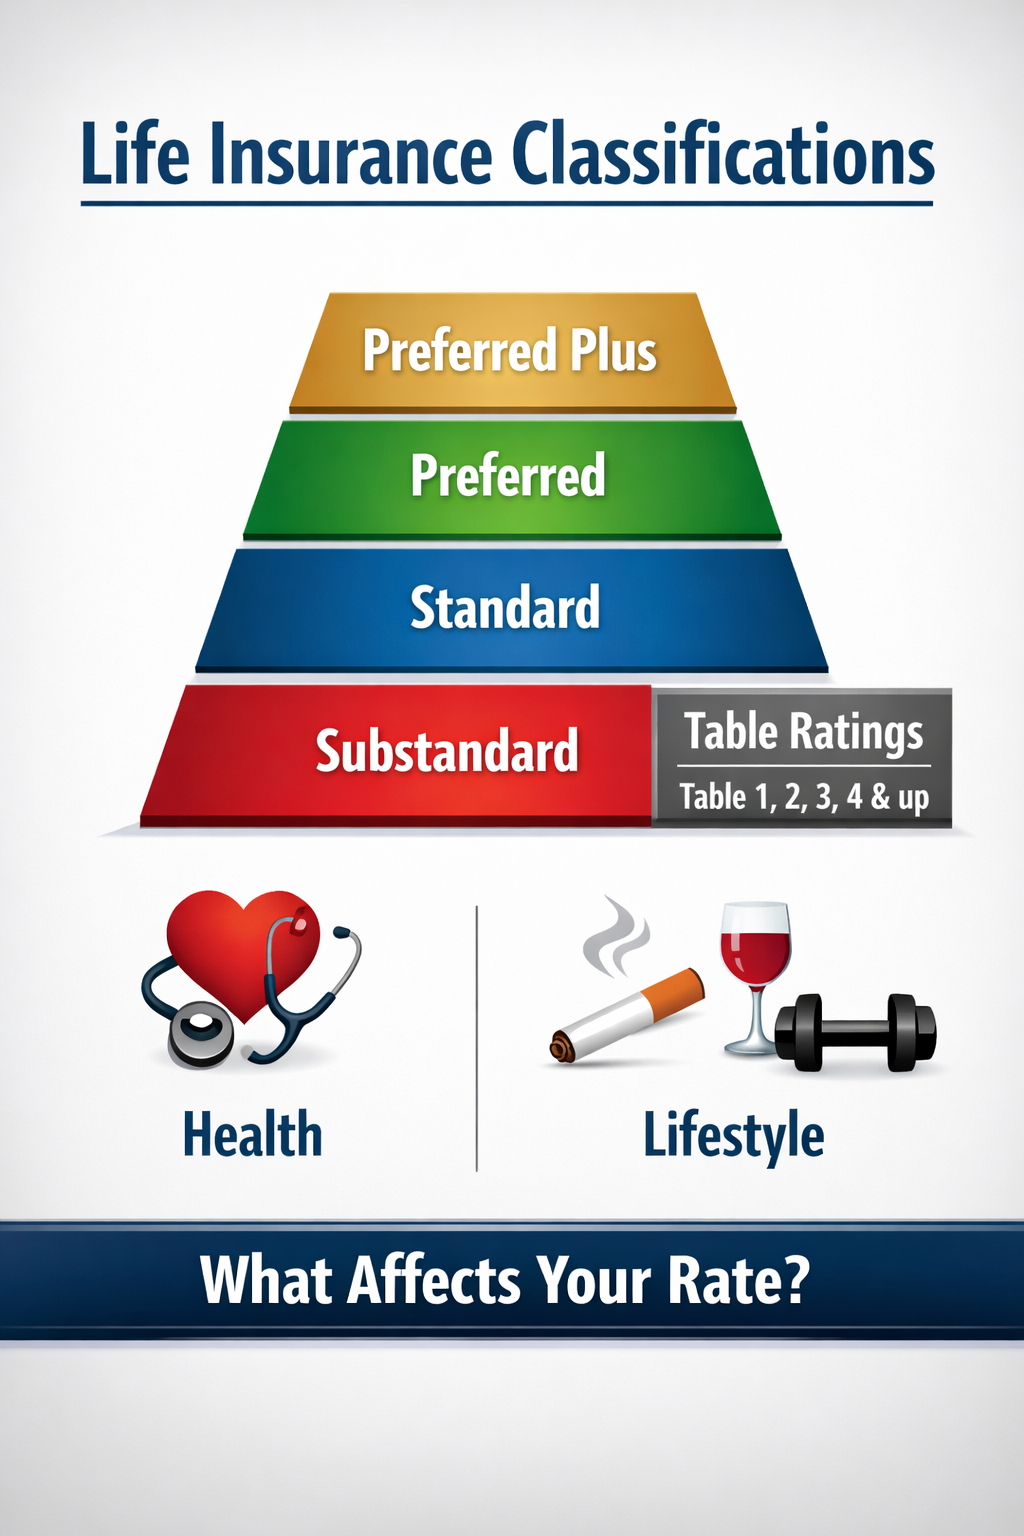
- What life insurance classifications mean
- The difference between Preferred Plus, Standard, and table ratings
- What affects your underwriting class
- When a case becomes table rated or declined
- How to improve your class before applying
What Are Life Insurance Classifications?
Life insurance classifications are underwriting categories insurers use to sort applicants by expected risk. In simple terms, they are the labels a company uses to decide how healthy or risky you look on paper.
The better your classification, the lower your premium is likely to be. The weaker your classification, the more you usually pay.
This is why two people applying for the same policy amount and term length can get very different prices.
Simple rule
- Better class = lower premium
- More risk = higher premium
- Table rating = approved, but priced up
- Declined = no offer from that carrier
The Most Common Life Insurance Rate Classes
Preferred Plus
The best class most companies offer. Usually reserved for applicants with very strong health, clean history, and low overall risk.
Preferred
Still a strong class, but not quite as clean as Preferred Plus. Many healthy buyers land here instead.
Standard Plus
Some companies use this middle tier for shoppers who are better than standard but do not quite fit preferred classes.
Standard
A common approval class for people with average health or moderate risk factors.
Table Rated / Substandard
You are still approved, but the insurer adds extra cost because the risk looks higher than standard.
Declined
The company decides not to offer coverage under its current underwriting rules.
What Is a Table Rating in Life Insurance?
A table rating means the insurer is willing to issue the policy, but not at standard pricing. Instead, it adds an extra charge because the application shows more risk than the company wants for a standard class.
Table ratings are often shown as Table A, Table B, Table C and so on, or with number equivalents depending on the carrier.
Table rated usually means
- You were not declined
- You did qualify for coverage
- The company priced in extra risk
- Another carrier may still classify you better
What Affects Your Life Insurance Classification?
Health history
Diagnoses, treatment, medications, and how stable a condition is all matter.
Height and weight
Build charts can affect which class a carrier is willing to offer.
Tobacco or nicotine
Nicotine use can push pricing much higher and change class options fast.
Family history
Some carriers look at serious hereditary health risks in close relatives.
Driving record
DUIs, reckless driving, and repeated violations can hurt your class.
Occupation and hobbies
High-risk jobs and dangerous hobbies can affect underwriting decisions.
Coverage amount
Larger face amounts can bring more underwriting scrutiny.
Carrier rules
Different companies can classify the same person differently.
Why Two Companies Can Rate You Differently
This is one of the most important things shoppers miss: classification is not identical across the market.
One company may offer Standard. Another may offer Table B. Another may still offer Preferred because it handles your situation more favorably.
That is why market comparison matters so much when health, weight, medications, tobacco, or past issues are involved.
Why comparison matters
- Carrier rules are not all the same
- Health conditions are weighted differently
- Some companies are more flexible than others
- The first offer is not always the best offer
Want to Know What Class You Might Qualify For?
A fast quote is useful, but a smarter quote is better. Compare options online or schedule a strategy call if you want help matching your profile to the right carriers first.
Classification vs Table Rated vs Declined
Standard or better
You qualified within the normal pricing bands the company offers.
Table rated
You still got approved, but the carrier added extra cost because the case looks riskier.
Declined
The company did not offer coverage, but that does not always mean every carrier will make the same decision.
How to Improve Your Life Insurance Classification
Apply at the right time
Sometimes waiting until treatment is stable or a health metric improves can make a real pricing difference.
Use the right carrier
Some companies are simply better fits for certain medical or lifestyle profiles.
Be accurate on the application
Clean, complete answers can help avoid delays and bad surprises later.
Consider no-exam carefully
No-exam paths are convenient, but they are not always the cheapest route for every profile.
For a better sense of the application flow, read Applying for Life Insurance →
Do No-Exam Policies Use Classifications Too?
Yes, but the process can look different. A no-exam policy may still use health questions, prescription history, medical databases, and other underwriting sources to sort risk.
Skipping the exam does not mean the company stops classifying risk. It just means it is using a different underwriting path.
No-exam still involves underwriting
- Health questions may still apply
- Prescription checks may still apply
- Risk is still classified
- Convenience may cost more in some cases
Helpful Next Pages
How Much Life Insurance Do I Need?
Use this if you still need to decide on your coverage amount before shopping quotes.
Open Coverage Guide →Life Insurance Online
Use this if you want to compare quotes and understand the online buying path next.
Open Online Buying Guide →How to Compare Life Insurance Quotes
Use this if you are already looking at offers and want to compare them the right way.
Open Quote Comparison Guide →Frequently Asked Questions About Life Insurance Classifications
What are life insurance classifications?
They are underwriting categories insurers use to group applicants by risk and decide pricing.
What is the best life insurance classification?
Usually Preferred Plus, though exact names and rules vary by company.
What does table rated mean in life insurance?
It means you were approved, but at a higher premium because the insurer sees more risk than it would for a standard class.
Can two companies give me different rate classes?
Yes. Different insurers often weigh health and lifestyle factors differently, which is why comparison shopping matters.
Does no-exam life insurance still use rate classes?
In many cases, yes. The underwriting path changes, but the insurer still evaluates risk and prices accordingly.
Understand Your Classification Before You Lock In a Price
The better you understand rate classes, the easier it becomes to compare quotes, choose the right carrier, and avoid overpaying for the same coverage.


