
Life Insurance Myths: 8 Costly Misconceptions and the Truth Behind Them
Most life insurance myths come from the same two places: people guessing at what coverage costs, and people repeating one weird story like it applies to everyone.
That is why this page matters. Families delay coverage because they think it is too expensive, they think work coverage is enough, or they assume buying life insurance is too complicated to deal with right now.
The real question is not just whether the myths are wrong. The real question is which misunderstanding is keeping you from buying the right coverage at the right time.
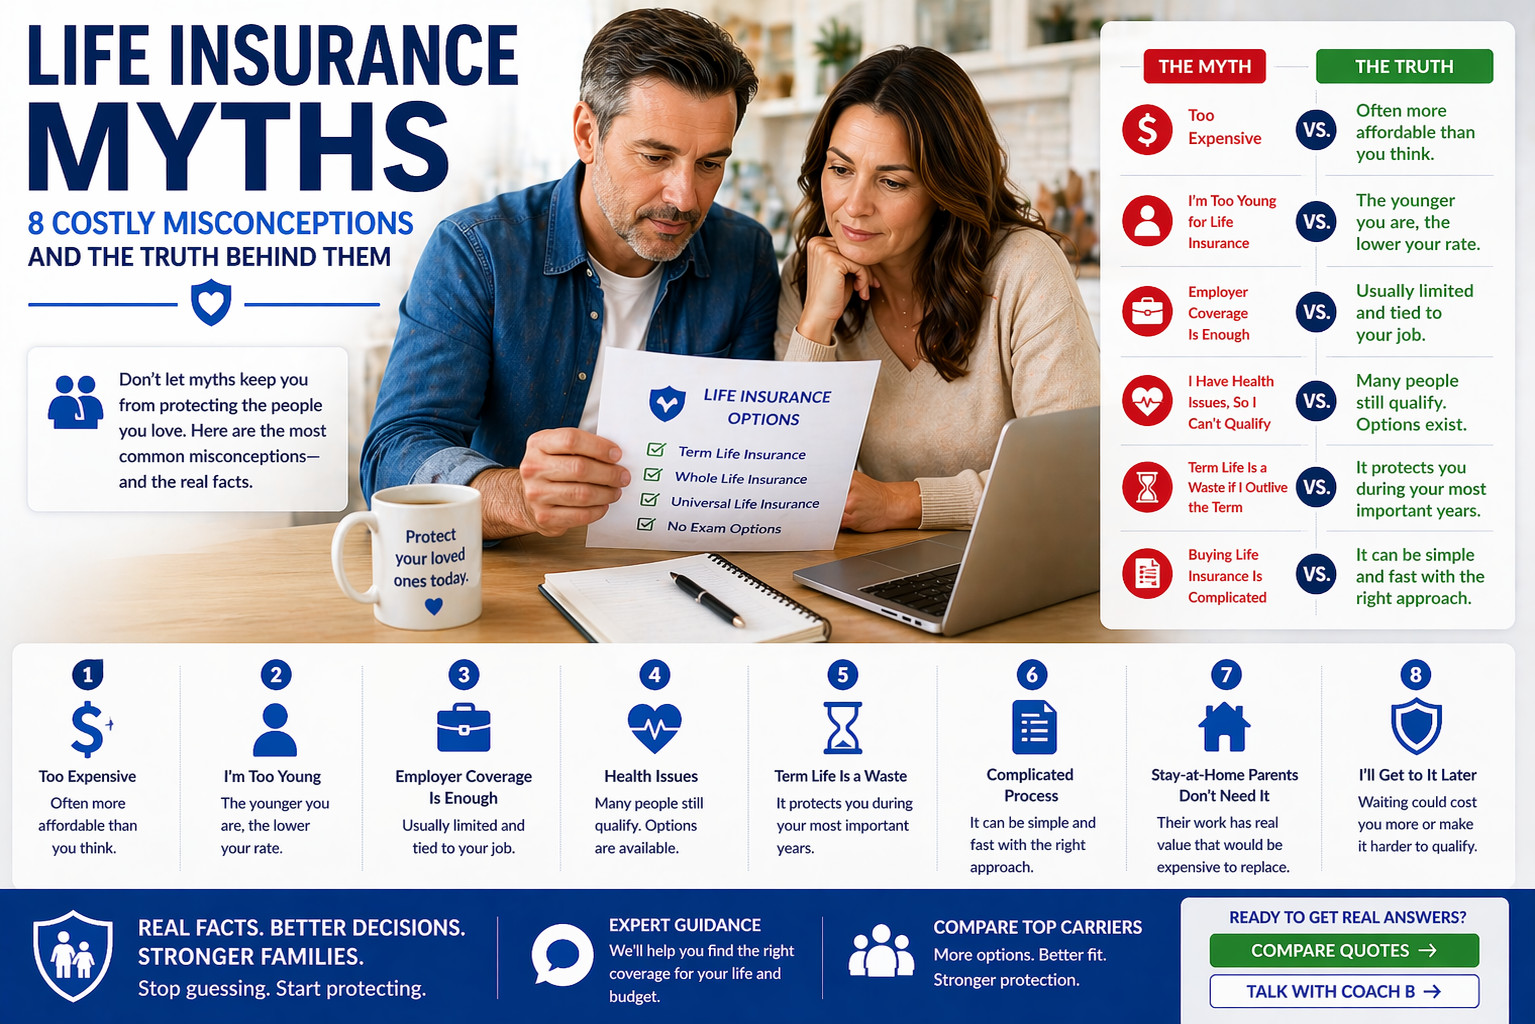
- Life insurance is often more affordable than people assume.
- Young and healthy is usually the best time to buy, not the time to wait.
- Employer coverage is often a helpful start, but usually not the finish line.
- Many people with health issues can still qualify for coverage.
- The smartest next step is moving from myth to a real quote, not guessing.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on product fit, underwriting clarity, and usefulness — not pressure.
Editorial note: This page is meant to handle the objections that stop people from moving forward. It is not the final buying page. It is the page that helps you stop guessing and start shopping intelligently.
The 8 Biggest Life Insurance Myths That Cost Families Money
These are the myths that show up over and over again in real conversations with buyers. Under each one, the better question is not just “is this true?” It is “what should I do next if it is not?”
Myth #1: “Life insurance is too expensive.”
Reality: For many families, especially term-life shoppers, it is often more affordable than they assume.
Why this myth hurts: People never get a real quote, so they reject coverage based on a guess instead of a number.
Best next step: Compare real quotes before deciding it is out of budget.
See real pricing factors →Myth #2: “I’m young and healthy, so I don’t need it yet.”
Reality: That is often the best time to buy because rates are usually lower before age and health complications change the picture.
Why this myth hurts: Waiting often means paying more later for the same basic protection.
Best next step: Look at term coverage while age and health are still working in your favor.
Explore term life options →Myth #3: “Only parents need life insurance.”
Reality: Parents are one major group, but not the only one. Spouses, co-signed debt, final expenses, business obligations, and caregiving roles can all create a need.
Why this myth hurts: People without kids often ignore real financial risk they still leave behind.
Best next step: Think about who would feel your financial loss, not just whether you have children.
Estimate your coverage need →Myth #4: “Stay-at-home parents don’t need life insurance.”
Reality: Childcare, transportation, meal prep, household management, and daily support all have real replacement cost.
Why this myth hurts: Families overlook unpaid work that would become very expensive overnight.
Best next step: Price out what it would actually cost to replace the work a stay-at-home parent does.
See stay-at-home parent coverage →Myth #5: “My employer life insurance is enough.”
Reality: Workplace coverage is often a good start, but it is commonly limited and tied to your job.
Why this myth hurts: People confuse “I have some coverage” with “I have enough coverage.”
Best next step: Compare your work policy against your real income-replacement and family needs.
See income replacement planning →Myth #6: “If I have health issues, I can’t get life insurance.”
Reality: Many people with health issues can still qualify. The real issue is usually pricing, carrier fit, and which product lane makes sense.
Why this myth hurts: Buyers rule themselves out before learning what is actually possible.
Best next step: Shop carriers and underwriting lanes instead of assuming the answer is no.
Compare no-exam paths →Myth #7: “Term life is a waste if I outlive it.”
Reality: Term life is designed to protect the years when the risk is biggest, like raising children, covering a mortgage, or replacing income.
Why this myth hurts: People reject the most affordable protection because they are judging it by the wrong job.
Best next step: Match term life to a temporary need, not to a permanent planning goal.
Compare term vs permanent →Myth #8: “Buying life insurance is complicated and takes forever.”
Reality: It can be simpler than people think, especially if you qualify for accelerated underwriting or no-exam options.
Why this myth hurts: People avoid starting because they imagine a long, painful process before they even see their real options.
Best next step: Start with a quick quote path and then decide whether you need a more detailed underwriting route.
See faster buying options →Why These Myths Keep Winning
People guess instead of quote
A lot of buyers never see real numbers, so the myth gets filled in by assumptions instead of facts.
Insurance feels unfamiliar
When people do not buy coverage often, a confusing process can feel bigger than it really is.
One story becomes “the rule”
A bad edge-case story gets repeated like it applies to every company and every buyer, when it usually does not.
How Coach B Would Use This Page
Step 1: find your biggest myth
The first move is figuring out which bad assumption is actually stopping you from shopping intelligently.
Step 2: move to the right spoke page
Each myth has a stronger next-step page that answers the buyer-intent question behind the hesitation.
Step 3: get a real quote
At some point, myth-busting has to turn into real comparison shopping. That is where the useful answer starts.
The Bottom Line
The biggest life insurance myths are expensive because they usually do not just create confusion. They create delay.
And delay is what makes coverage harder to buy, easier to avoid, and more expensive than it needed to be. The best fix is simple: stop guessing, match the myth to the real question behind it, and get an actual quote.
Helpful Related Pages
Life Insurance Buyer’s Guide
Best next page if you want the bigger education page after myth-busting the basics.
Open Buyer’s Guide →Life Insurance Rates
Best next page if your main hesitation is still price.
See Life Insurance Rates →Term vs Permanent Life Insurance
Best next page if your myth is really a product-choice question.
Compare Term vs Permanent →Life Insurance for Parents
Best next page if your main concern is protecting children and family cash flow.
See Life Insurance for Parents →No Medical Exam Life Insurance
Best next page if your myth is “I’ll never qualify because of my health.”
Explore No-Exam Options →Life Insurance for Stay-at-Home Parents
Best next page if your myth is “unpaid work does not count.”
See Stay-at-Home Parent Coverage →Life Insurance Online
Best next page if your myth is “buying takes forever.”
See Faster Buying Paths →Frequently Asked Questions
What are the most common life insurance myths?
The biggest myths are usually that life insurance is too expensive, only parents need it, employer coverage is enough, unhealthy people cannot qualify, and term life is a waste.
Is life insurance really more affordable than people think?
Often yes, especially term life insurance. A lot of people never see real quotes and assume the cost is much higher than it really is.
Is employer life insurance enough by itself?
Usually not for many families. It can be a good start, but it is often limited and tied to your job.
Can people with health issues still get life insurance?
Often yes. The real question is usually what price, what company, and what type of coverage make sense.
Is term life insurance a waste if you outlive it?
Usually no. It is designed to protect the years when your family and finances are most exposed, not necessarily to be permanent coverage forever.


