
Best Life Insurance Companies for Diabetics in 2026
The best life insurance company for a diabetic is usually not one universal brand. The right fit depends on whether you have type 1 or type 2 diabetes, whether you use insulin, how well your blood sugar is controlled, and whether you want term, no-exam, or final expense coverage.
This guide compares the best life insurance companies for diabetics by diabetic profile, policy type, and shopping goal so you can narrow down the right options with more confidence.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent (Coach B. Insurance)
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. This guide focuses on fit, underwriting practicality, and value.
Editorial note: Rates, issue ages, medical rules, and underwriting outcomes vary by company, state, and diabetic profile.
- Type 1 vs type 2 diabetes
- Age at diagnosis
- A1C and control history
- Insulin use and medications
- Complications and overall health
Best Life Insurance Companies for Diabetics at a Glance
| Category | Top Fit | Why It Stands Out | Best For |
|---|---|---|---|
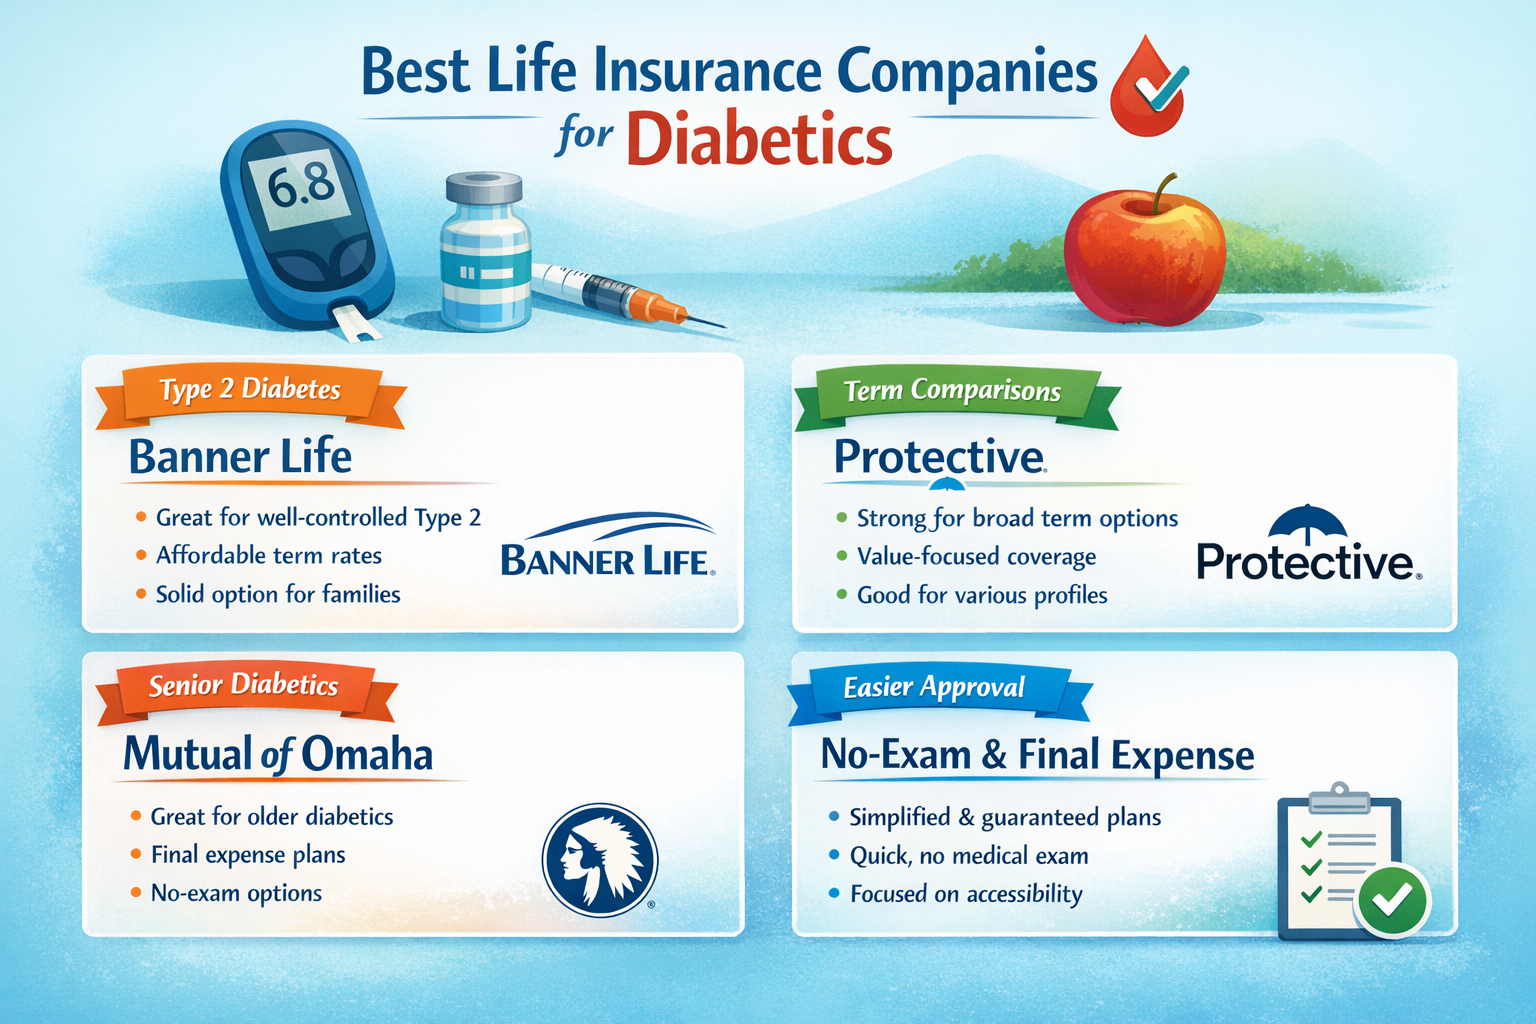
| Best for controlled type 2 diabetes | Banner Life | Often worth comparing when diabetes is controlled and term value matters | Mainstream type 2 shoppers |
| Best for broad diabetic term comparisons | Protective | Often relevant when shopping traditional term options with diabetes | Value-focused shoppers |
| Best for seniors with diabetes | Mutual of Omaha | Senior-market and simpler-product relevance can matter | Older diabetic shoppers |
| Best for no-exam comparisons | Case-by-case | No-exam fit depends heavily on the diabetic profile | Convenience-focused buyers |
| Best for harder health profiles | Simplified or final expense | Accessibility may matter more than perfect pricing | Shoppers with complications |
The right winner changes depending on diabetic type, control history, insulin use, age, and whether the goal is term life, no-exam coverage, or final expense.
How We Chose the Best Life Insurance Companies for Diabetics
Underwriting fit
Some carriers are more useful for controlled type 2 cases, while others make more sense for senior or simplified shopping.
Policy usefulness
We look at whether the product actually fits real goals like family protection, mortgage coverage, or final expenses.
No-exam flexibility
Some diabetic shoppers care more about convenience than pursuing the strongest traditional underwriting result.
Value
The best company is the one most likely to approve the right policy at a realistic premium for the diabetic profile.
Best Companies for Type 2 Diabetes
Banner Life
Banner is often worth comparing for controlled type 2 diabetes, especially when the shopper wants traditional term-life value and the overall health picture is stable.
Explore Banner Life Review →Why it can fit type 2 shoppers
- Relevant for traditional term shopping
- Can be a strong quote benchmark
- Worth testing when diabetes is controlled
- Useful for family-protection needs
Best Companies for Broad Diabetic Term Comparisons
Protective
Protective is often a strong company to compare when a diabetic shopper still wants traditional term life and is trying to see which carrier offers the better fit and value.
Explore Protective Review →Why it belongs in the comparison set
- Strong term comparison carrier
- Useful for value-focused shopping
- Worth testing for diabetics who still fit traditional underwriting well
- Good benchmark against Banner
Best for Seniors With Diabetes
Mutual of Omaha
Mutual of Omaha is often a strong comparison point for older diabetic shoppers because senior-market fit, simpler products, and no-exam or final-expense relevance can matter more at older ages.
Explore Mutual of Omaha Review →Why it can fit older diabetic shoppers
- Senior-market relevance
- No-exam appeal
- Useful final-expense comparisons
- Good fit when accessibility matters
Best for No-Exam Diabetic Shopping
No-exam life insurance
Best when convenience matters more than chasing the absolute best traditional rate class.
Simplified issue options
Best when you can answer some health questions and may not need full guaranteed acceptance.
Final expense or guaranteed issue
Best when accessibility matters more than maximum coverage or pure term value.
What Life Insurance Companies Usually Look At for Diabetes
| Factor | Why It Matters | General Impact |
|---|---|---|
| Type 1 vs type 2 | Different diabetic histories can create different underwriting patterns | Usually a major factor |
| Age at diagnosis | Earlier diagnosis can affect how risk is viewed | Often important |
| A1C and control history | Shows how well blood sugar is being managed | Usually very important |
| Insulin use | Can change carrier fit and pricing outcomes | Important but not always a dealbreaker |
| Complications | Kidney, eye, nerve, or cardiovascular issues can change the case fast | Can materially affect options |
When Diabetics Should Compare Term vs No-Exam vs Final Expense
Term life
Best when you want larger family-protection coverage and your diabetic profile still fits traditional underwriting well.
No-exam life
Best when speed and convenience matter more than pursuing the strongest fully underwritten result.
Final expense
Best when the main goal is burial costs, final bills, or a simpler permanent policy.
Want Help Finding the Best Life Insurance Company for Your Diabetes Profile?
Compare quotes online or schedule a strategy call if you want help matching your diabetic history, age, and coverage goal to the right company before you apply.
Helpful Related Pages
Life Insurance Quotes for Diabetics
Best next page if you want the full diabetic-quote guide.
Explore Diabetic Quotes Guide →Best No Exam Life Insurance Companies
Best next page if convenience and speed matter most.
Explore Best No Exam Companies →How to Compare Life Insurance Quotes
Best next page if you want a better process for judging diabetic quotes.
Explore Quote Comparison Guide →Best Life Insurance Companies
Best next page if you want the broader carrier roundup.
Explore Best Life Insurance Companies →Frequently Asked Questions About the Best Life Insurance Companies for Diabetics
What is the best life insurance company for diabetics?
There is not always one universal winner. The best company usually depends on whether you have type 1 or type 2 diabetes, whether you use insulin, and how well your diabetes is controlled.
Can diabetics still get term life insurance?
Yes, in many cases. Controlled diabetics may still qualify for traditional term life, depending on the overall health picture and the carrier.
Are no-exam policies better for diabetics?
Sometimes, but not always. No-exam coverage may be better when speed and convenience matter most, while traditional underwriting may offer better value for some shoppers.
Do insulin users have fewer options?
Sometimes they may, but insulin use does not automatically mean there are no options. Carrier fit still matters a lot.
What matters most to life insurance companies when you have diabetes?
They usually look closely at diabetic type, age at diagnosis, A1C and control history, insulin use, complications, and the overall health profile.


