
Health Conditions and Life Insurance: How Medical History Affects Approval and Rates
Yes, many people with health conditions can still qualify for life insurance. The bigger issue is usually how insurers view the severity, stability, treatment history, and overall risk profile behind the diagnosis.
This guide explains how medical history can affect approval and pricing, how underwriters usually look at common conditions, and where to start if you are shopping with high blood pressure, sleep apnea, depression, bipolar disorder, anxiety, smoking history, or other health issues.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent (Coach B. Insurance)
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on fit, underwriting, and clarity — not pressure.
Editorial note: This article is educational. Underwriting rules, rate classes, exam requirements, and product availability vary by carrier, product, and state.
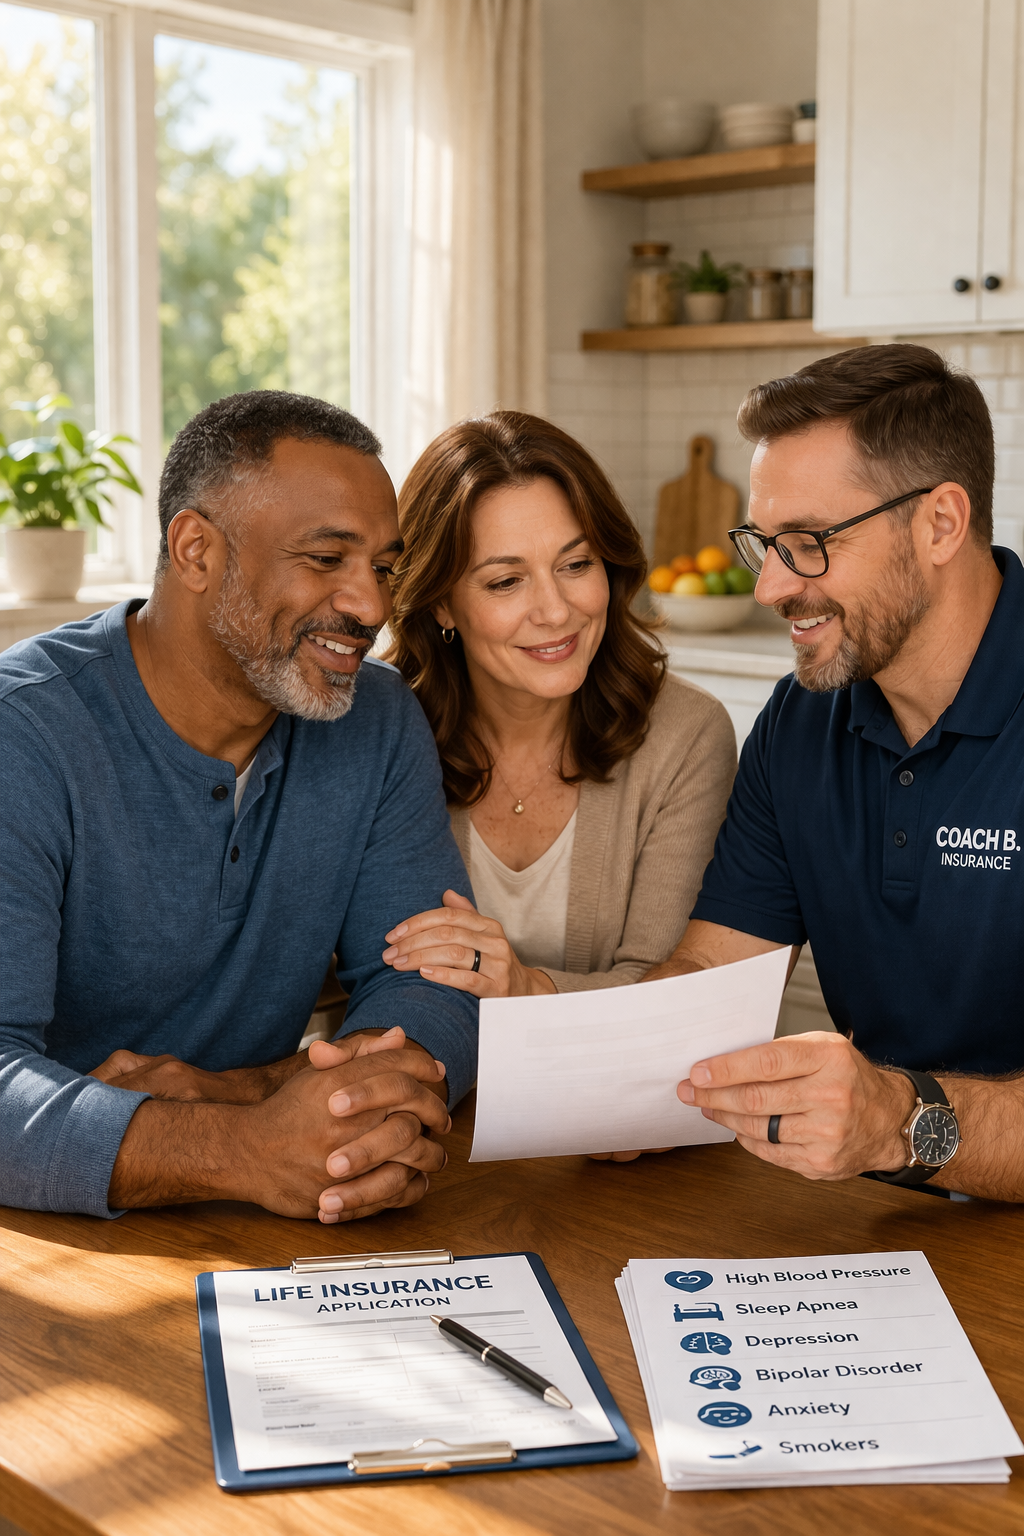
- Diagnosis history and severity
- Treatment and medication stability
- Whether the condition is controlled
- Related health concerns
- Your overall underwriting profile
Can You Get Life Insurance With Health Conditions?
Yes. Many people with medical or mental health conditions can still get life insurance. The diagnosis alone usually does not tell the whole story. Insurers often care more about how serious the condition is, whether it is controlled, what treatment looks like, and whether there are other related risks in the profile.
Two people with the same diagnosis can get very different results if one has stable treatment and strong overall health while the other has recent complications, hospitalizations, or multiple conditions interacting together.
Direct answer
- Yes, many applicants can still qualify
- Controlled conditions often help
- Medication is not automatically a problem
- Carrier selection matters more than many people think
How Health Conditions Affect Life Insurance Approval
Severity matters
Mild, moderate, and more serious histories are often treated very differently in underwriting.
Stability matters
A stable condition with clear treatment history is often viewed more favorably than a recent, changing, or unmanaged condition.
Related risks matter too
Weight, tobacco use, blood pressure, medications, mental health history, and other diagnoses all influence the final picture.
How Health Conditions Affect Life Insurance Rates
| Health Situation | What Insurers Usually Focus On | General Impact |
|---|---|---|
| Mild and controlled condition | Stable readings, treatment consistency, no major recent issues | Often more favorable than people expect |
| Moderate but managed condition | How long it has been controlled and whether there are related risks | May lead to a higher rate class but still be workable |
| Recent, severe, or unstable condition | Hospitalizations, medication changes, complications, functional impact | Usually creates more underwriting concern |
| Multiple health concerns together | The full underwriting profile, not just one diagnosis | Carrier choice becomes even more important |
Medical Exam vs No-Exam Life Insurance With Health Problems
Traditional fully underwritten life insurance often gives the most detailed view of your profile, which can be good when your condition is controlled and you want the best possible rate class available to you.
No-exam options may be useful in some cases when convenience matters more, when you want to avoid paramed testing, or when a simplified underwriting path fits better. But pricing and approval logic can vary a lot by product.
General pattern
- Fully underwritten can reward strong control and stability
- No-exam can help in some convenience-driven situations
- Not every condition fits every carrier the same way
- Product choice matters as much as condition type
Common Health Conditions and Related Guides
High Blood Pressure
Learn how controlled vs uncontrolled blood pressure can affect approval and rate class.
Explore High Blood Pressure Guide →Sleep Apnea
See how treatment, CPAP use, and severity can affect life insurance underwriting.
Explore Sleep Apnea Guide →Depression
Understand how medication, therapy, stability, and overall mental health history may be reviewed.
Explore Depression Guide →Bipolar Disorder
Review how episode history, hospitalization, medication, and stability may affect approval.
Explore Bipolar Guide →Anxiety
See how anxiety treatment, panic history, medications, and stability may affect pricing.
Explore Anxiety Guide →Smoking / Nicotine Use
Learn how tobacco and nicotine use can affect rates, underwriting, and future re-shopping options.
Explore Smokers Guide →How to Shop Smarter If You Have Health Conditions
Know your diagnosis details
Dates, medications, severity, treatment, and recent stability all matter more than rough assumptions.
Be accurate on the application
Clear answers matter. Do not minimize diagnosis or treatment history.
Compare more than one carrier
Different insurers may view the same condition profile very differently.
Look at the full picture
Age, tobacco use, medications, blood pressure, weight, and other conditions all work together in underwriting.
Want Help Finding Life Insurance With Health Conditions?
Compare quotes online or schedule a strategy call if you want help matching your medical history, treatment profile, budget, and coverage needs to the right life insurance options.
Frequently Asked Questions About Health Conditions and Life Insurance
Can you get life insurance with pre-existing conditions?
Yes. Many people with pre-existing conditions can still qualify for life insurance, especially when the condition is controlled and the overall profile appears stable.
Do medications automatically hurt life insurance approval?
Usually not by themselves. In many cases, treatment can help show that a condition is being managed responsibly.
Do health conditions always mean higher life insurance rates?
Not always at the same level. The rate impact depends on severity, treatment stability, related risks, and the insurer’s underwriting rules.
Is no-exam life insurance better if you have health problems?
Not always. In some cases it may help, but in other cases fully underwritten coverage may actually fit better if the condition is controlled and the underwriting outcome is favorable.
What matters most besides the diagnosis itself?
Insurers also look at treatment, stability, medications, related conditions, tobacco use, age, and the overall underwriting profile.


