
How Many Life Insurance Policies Can You Have? Laddering, Limits, and When Multiple Policies Make Sense
Yes, you can usually have more than one life insurance policy. The real issue is not the number of policies. The real issue is whether the total coverage still makes sense for your income, your obligations, and your insurable need.
That is why this page matters. Most shoppers are not just asking whether multiple policies are allowed. They are asking whether they can own policies with different companies, whether laddering is smart, and what happens if they already have work coverage or an existing personal policy.
The real question is not just how many life insurance policies you can have. The real question is when multiple policies create a smarter protection plan and when they just create extra premium cost.
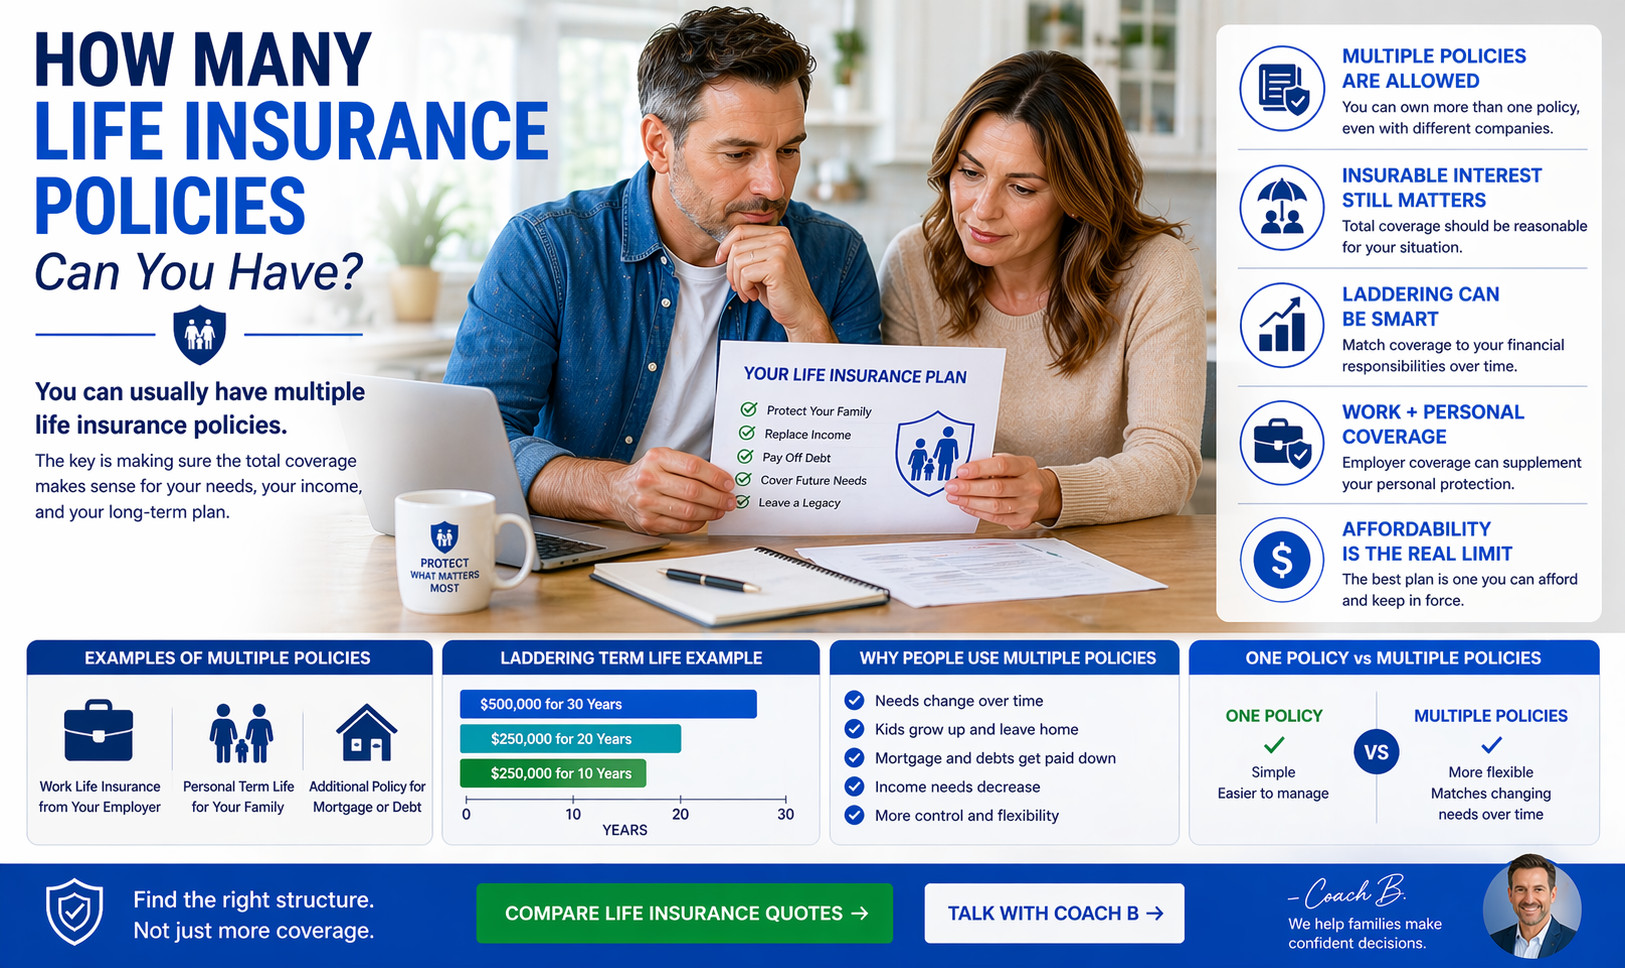
- You can usually own multiple life insurance policies, even with different companies.
- There is usually not a simple legal cap on the number of policies.
- Insurers still look at your existing coverage and whether the total amount is reasonable.
- Multiple policies can make sense when your protection needs change over time.
- Laddering term policies is often the smartest version of “multiple policies” for families.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on fit, underwriting clarity, and usefulness — not pressure.
Editorial note: This page is the multiple-policies and laddering guide. It is not the same as “how much coverage do I need?” That is a different planning question. This page is about structuring coverage once you already know the job the insurance needs to do.
Can You Have More Than One Life Insurance Policy?
Yes. In most cases, you can have multiple life insurance policies at the same time. That can include more than one personal policy, a mix of work and personal coverage, or policies from different carriers.
Same person, multiple policies
Owning more than one policy is usually allowed.
Different companies is possible
You do not necessarily have to keep all coverage with one carrier.
Work + personal is common
A group policy can sit on top of a personal policy.
Need still matters
Insurers still review whether the total coverage is supportable for your situation.
What Usually Limits Multiple Policies?
| Potential Limit | What It Means | Why It Matters |
|---|---|---|
| Insurable interest | Life insurance is meant to protect against real financial loss, not create a windfall | Coverage still has to make sense for the person insured |
| Existing coverage review | Insurers may look at what policies you already have in force | They want to understand the total death benefit picture |
| Financial justification | Total coverage generally needs to line up with income, debt, dependents, and obligations | Too much coverage can trigger extra questions or limits |
| Affordability | Even if coverage is allowed, you still have to sustain all the premiums | Too many policies can become a budgeting mistake |
The practical limit is usually not “you can only have X policies.” It is whether the coverage is justified and manageable.
When Multiple Life Insurance Policies Actually Make Sense
Needs changed over time
A policy you bought years ago may no longer be enough after marriage, kids, a bigger mortgage, or higher income.
Work coverage is not enough
Employer life insurance often works better as a supplement than a full solution.
Different jobs for different policies
One policy may cover family income replacement while another handles final expenses or a specific debt timeline.
Laddering strategy
Some buyers intentionally stack smaller term policies with different end dates to match how obligations fall over time.
What Is Life Insurance Laddering?
The simple version
Laddering means buying more than one term policy with different lengths instead of one single giant policy. The goal is to line up more coverage with your highest-risk years and less coverage as debts and responsibilities fall away.
Why people do it
Laddering can create a more tailored protection plan. For example, you may want more coverage while kids are young and the mortgage is high, but less coverage later when the financial burden is smaller.
| Example Ladder | Purpose |
|---|---|
| $500,000 for 30 years | Core long-range family protection |
| $250,000 for 20 years | Extra income replacement during child-raising years |
| $250,000 for 10 years | Shorter-term protection for specific debts or early family risk |
One Big Policy vs Multiple Smaller Policies
| Approach | Main Strength | Main Tradeoff |
|---|---|---|
| One large policy | Simpler to manage and easier to track | Less flexible if your needs change in stages |
| Multiple policies | Can match different obligations more precisely | More moving parts and more premium decisions |
| Laddered term setup | Can align cost with changing family risk over time | Takes more planning to get the structure right |
When Multiple Policies Are Usually a Bad Idea
Bad fit if…
- you are stacking policies without a clear reason
- the total premium is stretching your budget
- you are overinsuring far beyond your real need
- one cleaner policy would solve the problem just as well
Often better to simplify if…
- your needs are straightforward
- you only want one primary family-protection goal covered
- you do not want to track several policy dates and terms
- your existing policy can be expanded appropriately instead
How Coach B Would Shop This
Step 1: find the real coverage target
Before adding another policy, I would first define the total amount of protection you actually need.
Step 2: decide if one policy or a ladder is cleaner
If your obligations fall in stages, laddering may make sense. If not, one well-built policy may be better.
Step 3: make sure the total structure is still affordable
The smartest plan is the one you can keep in force without premium strain.
The Bottom Line
You can usually have more than one life insurance policy, and sometimes multiple policies are the smartest way to build coverage.
But more policies are not automatically better. The goal is to match your protection to your real financial obligations, not just accumulate death benefit. If multiple policies help you do that more efficiently, great. If one simpler setup does the job, that may be the better move.
Helpful Related Pages
Life Insurance Calculator
Best next page if you still need to define the total amount of coverage before deciding whether one or more policies make sense.
Use the Coverage Calculator →Life Insurance for Income Replacement
Best next page if your main reason for stacking policies is replacing family income properly.
See Income Replacement Guide →Term Life Hub
Best next page if you want to see the main term options used in laddering strategies.
Explore Term Life →Applying for a Life Insurance Policy
Best next page if you want the underwriting and application process explained before adding more coverage.
See the Application Process →Frequently Asked Questions
Can you have more than one life insurance policy?
Yes. In most cases you can have multiple policies, including policies with different companies.
Is there a legal limit to how many life insurance policies you can have?
Usually no simple fixed legal limit, but insurers still review whether the total coverage amount is justified.
Can you have life insurance policies with different companies?
Yes, that is usually possible. Multiple policies do not have to all come from one insurer.
What is laddering life insurance?
Laddering means using multiple policies, often term policies with different lengths, to match changing financial obligations over time.
When do multiple life insurance policies make sense?
They often make sense when needs have changed, work coverage is not enough, or a laddering strategy better matches how your financial responsibilities decline over time.


