
Types of Life Insurance Policies: What They Are, Who They Fit, and How to Choose
Most life insurance falls into two big buckets: temporary coverage and permanent coverage. From there, the different policy types matter because each one is built for a different job.
That is why this page matters. Most buyers are not really asking for definitions alone. They are trying to figure out which kind of life insurance actually fits their family, budget, health situation, and long-term goals.
The real question is not just what the types of life insurance policies are. The real question is which type matches the job you need life insurance to do.
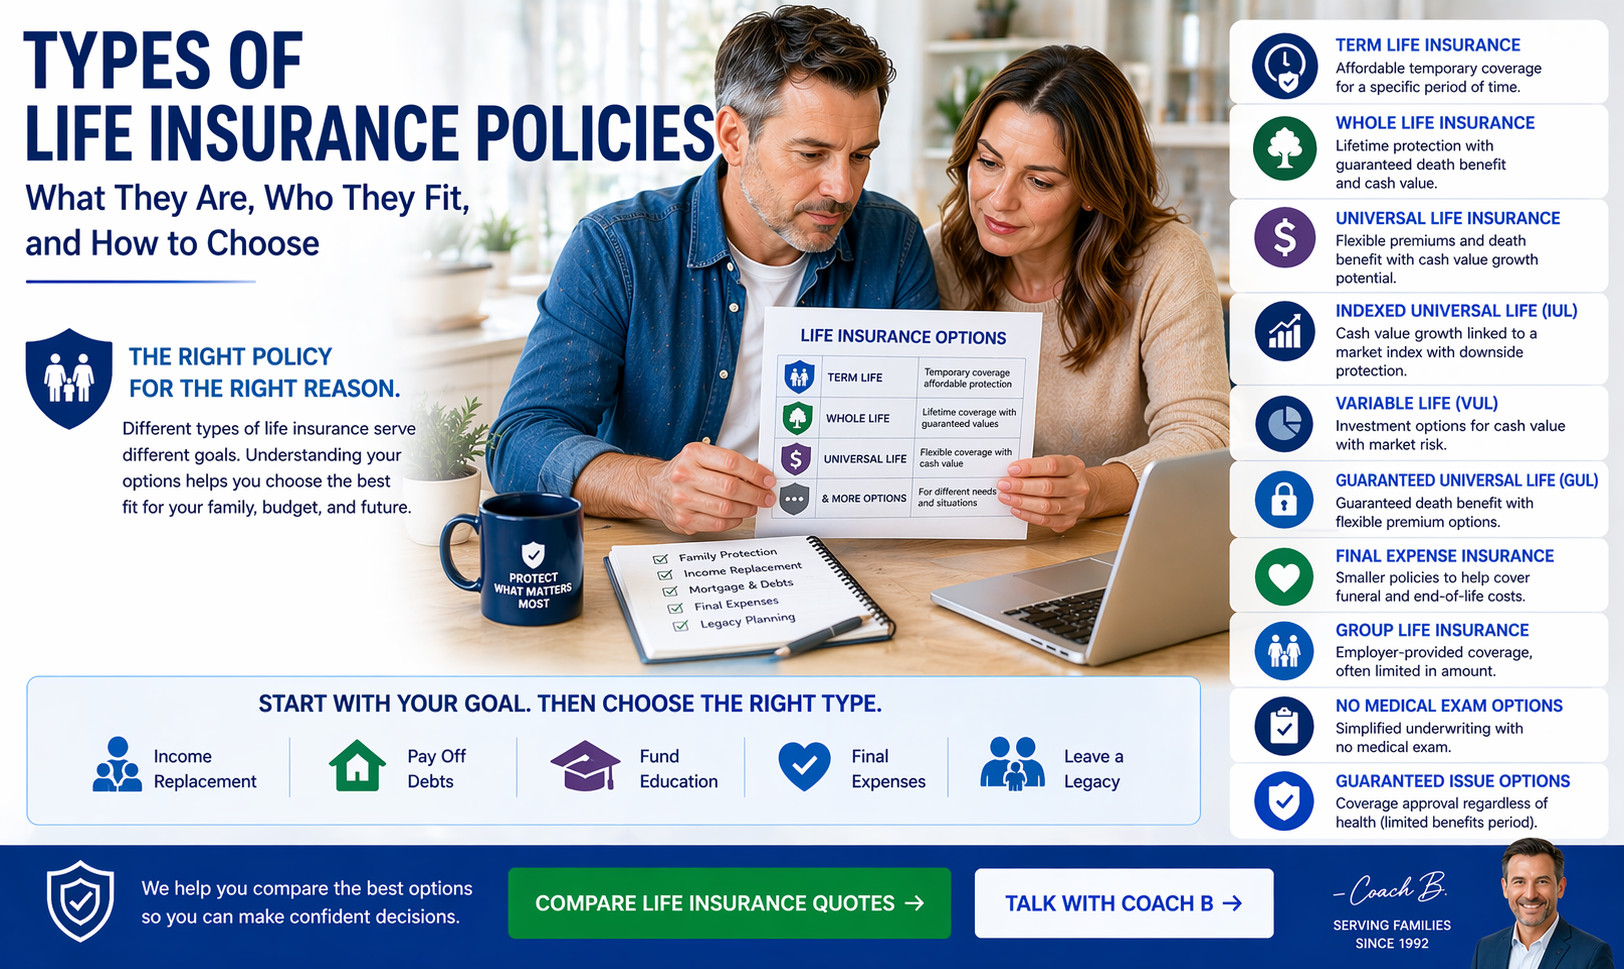
- The main split is usually term life versus permanent life.
- Permanent life includes whole life, universal life, and related variations like IUL, VUL, and GUL.
- Final expense is usually a smaller permanent coverage lane.
- Group life is often employer-based baseline coverage.
- No-exam and guaranteed issue are usually underwriting paths, not always separate core policy families.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on fit, underwriting, and usefulness — not pressure.
Editorial note: This page is the policy-types explainer. It is meant to help you understand the menu of options first, then move you into the right hub for the deeper quote, cost, and fit questions.
The 2 Big Categories: Term vs Permanent Life Insurance
The simplest way to understand life insurance types is to start with the two major categories:
Term life insurance
Temporary coverage for a set period, usually 10, 20, or 30 years. It is often the best fit when the job is income replacement, debt protection, or family protection during a specific time window.
Permanent life insurance
Coverage designed to stay in force long term or for life, as long as the policy is managed correctly and kept in force. This category often includes cash value or other long-term planning features.
Quick Visual: Where Most Policy Types Fit
Availability and exact product names can vary by carrier and state, but this is the general structure most buyers will run into.
The Main Types of Life Insurance Policies
1) Term Life Insurance
Best for affordable temporary protection, income replacement, kids, mortgage years, and big coverage on a budget.
2) Whole Life Insurance
Best for buyers who want permanent coverage, predictable structure, and a policy they intend to keep long term.
3) Universal Life Insurance
Best for permanent coverage with more flexibility than whole life, but with more moving parts too.
4) Final Expense Insurance
Best for smaller permanent coverage focused on funeral, burial, and end-of-life expenses.
5) Group Life Insurance
Best for employer-based baseline coverage, but often not enough by itself for a family.
6) No Medical Exam Life Insurance
Best for buyers who want a faster, simpler underwriting path. This is often a coverage path more than a single policy family.
7) Guaranteed Issue Life Insurance
Best for very hard-to-insure buyers who need a no-health-question option and understand the tradeoffs.
8) Other Permanent Variations
This bucket includes IUL, VUL, GUL, and other specialized permanent designs with more specific use cases.
What Each Type Usually Fits Best
| Policy Type | Usually Best For | Main Tradeoff |
|---|---|---|
| Term life | Income replacement, mortgage protection, family years, large affordable death benefit | Coverage ends after the term |
| Whole life | Permanent protection and structured long-term planning | Higher premiums than term |
| Universal life | Permanent coverage with more flexibility | More complexity and funding risk |
| IUL / VUL / GUL | Specific permanent-planning needs depending on the design | More specialized and easier to misunderstand |
| Final expense | Burial and end-of-life cost protection | Smaller face amounts |
| Group life | Baseline work coverage | May not be portable or sufficient |
| No-exam | Faster, easier approval path | Can cost more or offer fewer options in some cases |
| Guaranteed issue | Very hard-to-insure shoppers | Usually the highest cost for the least immediate protection |
The Specialized Permanent Types People Ask About Most
Indexed Universal Life (IUL)
Often discussed for cash value growth tied to an index-crediting approach, but contract details matter a lot.
Variable Life / VUL
Usually for buyers who understand investment risk and want market-linked subaccount exposure inside the policy.
Guaranteed Universal Life (GUL)
Often used for permanent death-benefit protection with fewer moving parts than cash-value-heavy designs.
Survivorship / Joint Policies
More specialized policies that usually fit estate or two-person planning situations rather than basic family term needs.
How to Choose the Right Type of Life Insurance
Start with term if…
- you need a big death benefit on a budget
- your main job is income replacement, kids, or a mortgage
- your need is temporary rather than lifelong
- you want simpler, more straightforward coverage
Look harder at permanent if…
- you want coverage intended to last for life
- you have legacy, final expense, or longer-term planning goals
- you are comfortable paying more for permanent protection
- you actually want the features the permanent policy is built to provide
Best Next Page by Policy Type
Term Life Insurance
Best next page if affordable temporary coverage is probably your main fit.
Explore Term Life →Whole Life Insurance
Best next page if you want a structured permanent policy and cash value discussion.
Explore Whole Life →Universal Life Insurance
Best next page if you want flexible permanent coverage and need to understand UL, IUL, VUL, and GUL better.
Explore Universal Life →Final Expense Insurance
Best next page if your goal is burial, funeral, and end-of-life expense planning.
Explore Final Expense →No Medical Exam Life Insurance
Best next page if speed and simpler underwriting matter more than full underwriting.
Explore No-Exam Options →Guaranteed Issue Life Insurance
Best next page if health makes other approval paths much harder and you need a last-resort option.
Explore Guaranteed Issue →Life Insurance Buyer’s Guide
Best next page if you need the broader buying framework after understanding the main policy types.
Open Buyer’s Guide →The Bottom Line
The best type of life insurance is not the one with the fanciest name. It is the one that fits the actual job your coverage needs to do.
For many families, that means term life. For others, it may mean permanent coverage, final expense, no-exam, or guaranteed issue. Start with the type that matches your need, then compare the best options inside that lane.
Frequently Asked Questions
What are the main types of life insurance?
The most common types are term life, whole life, universal life, final expense, group life, and specialized permanent variations like IUL, VUL, and GUL.
What is the difference between term and permanent life insurance?
Term life is temporary coverage for a set number of years, while permanent life is designed for longer-term or lifelong protection if kept in force properly.
What type of life insurance is usually best for families on a budget?
For many families, term life insurance is the strongest first place to look because it usually offers the largest death benefit for the lowest cost.
Is no medical exam life insurance its own type?
Usually it is better thought of as an underwriting path or approval lane rather than one single core policy family.
What type of life insurance is best overall?
There is no one best type for everyone. The best fit depends on whether your need is temporary, permanent, health-driven, budget-driven, or focused on final expenses.


