
The Truth About MIB Insurance Report: What Insurers See and What You Can Request
If you are applying for life insurance, the MIB report is one of those behind-the-scenes underwriting tools that can make people nervous fast.
That is why this page matters. Most shoppers are not just asking what MIB is. They are asking what life insurance companies actually see, whether MIB can hurt an application, whether it is the same thing as medical records, and how to get a copy of their own file.
The real question is not just what an MIB insurance report is. The real question is how MIB fits into the underwriting process and what you should do if the information in your file is wrong or misunderstood.
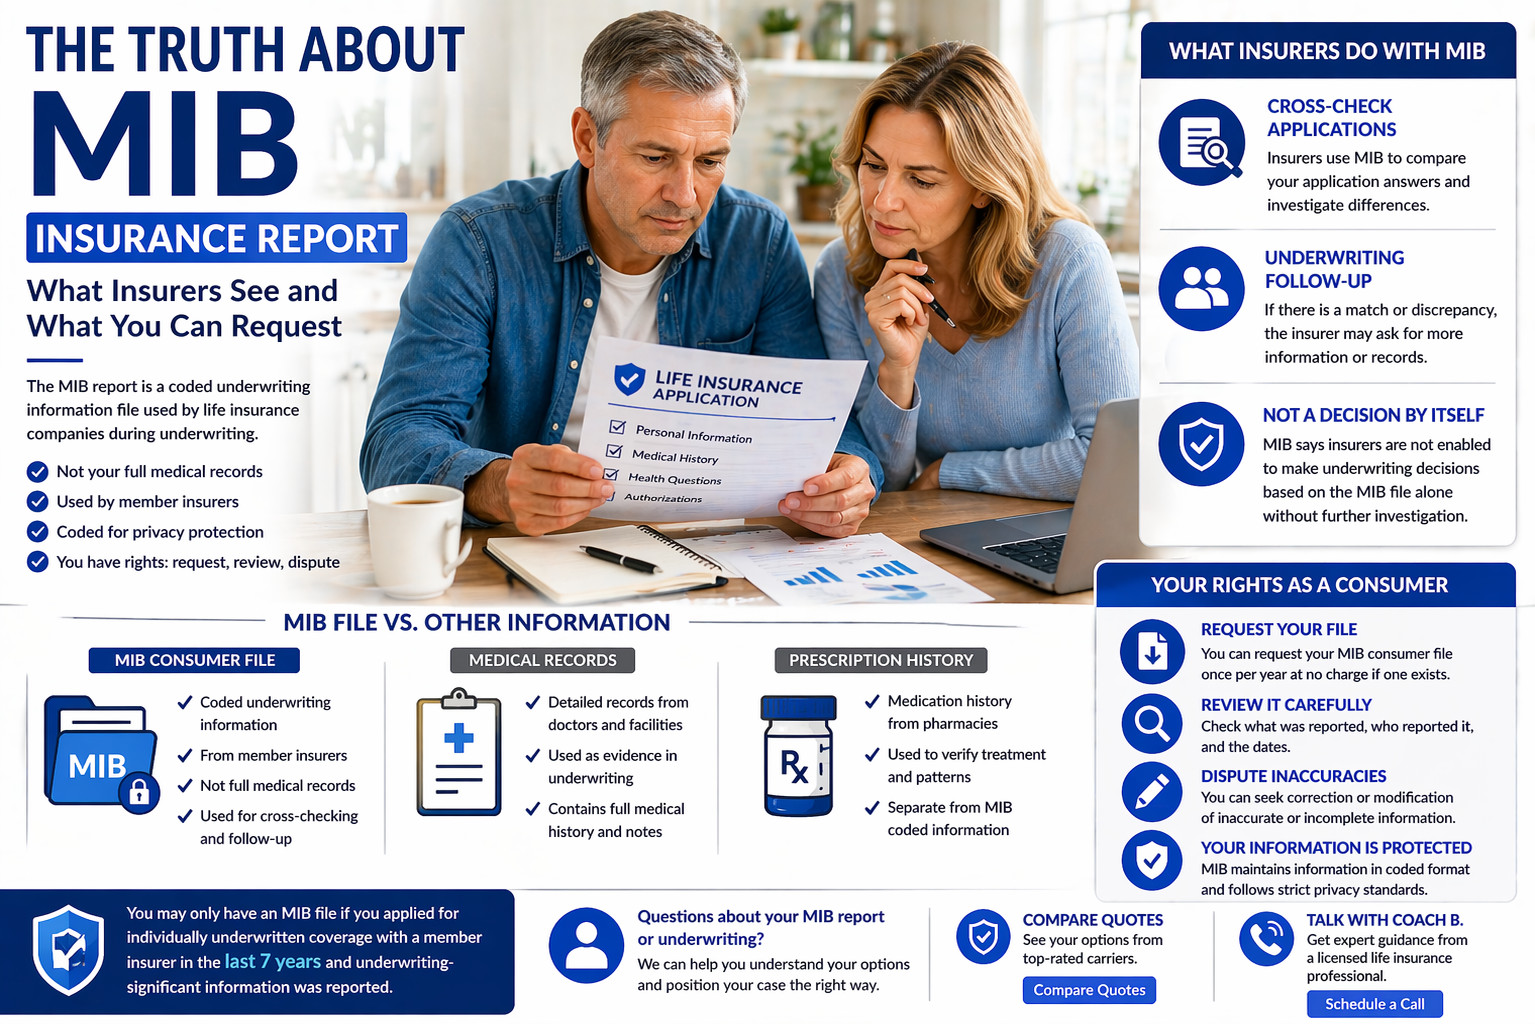
- MIB is not the same thing as your full medical records.
- MIB information is maintained in coded format and used by member carriers during underwriting.
- You may only have an MIB file if you applied for individually underwritten coverage with a member carrier in the last 7 years.
- You can request your MIB consumer file once a year at no charge if one exists.
- MIB information can raise underwriting questions, but it is not supposed to be the only basis for a final underwriting decision.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on product fit, underwriting, clarity, and usefulness — not pressure.
Editorial note: The MIB report gets talked about like it is some secret blacklist. It is not. But it is important, because it can affect how an insurer cross-checks your application and follows up on underwriting questions.
What MIB Is and What It Is Not
MIB is a specialty consumer reporting system used by participating insurance companies during underwriting. It is not your full medical chart, not your prescription database, and not a simple approval-or-denial machine by itself.
What it is
A database of coded underwriting information used by member carriers when you apply for coverage.
What it is not
It is not a full copy of your doctor records or a complete medical history file.
How it is stored
MIB says applicant information is maintained in coded format for privacy protection.
Why insurers use it
Carriers use it to cross-check application information and investigate discrepancies.
How MIB Usually Affects Life Insurance Underwriting
| Underwriting Step | How MIB Fits In | Why It Matters |
|---|---|---|
| Application review | The carrier may compare your application answers against coded MIB information. | This can flag differences that need follow-up. |
| Underwriting investigation | If something does not match, the carrier may ask more questions or request more evidence. | The issue is usually the discrepancy, not just the existence of an MIB code. |
| Final decision | MIB says carriers are not enabled to make underwriting decisions based on the file alone without further investigation. | This is why context matters so much. |
| Future applications | New underwriting findings may be reported back by member carriers. | What happens on one application can matter later if you reapply elsewhere. |
When You May Actually Have an MIB Consumer File
Usually yes if…
You applied for individually underwritten life insurance with an MIB member carrier in the last 7 years and underwriting-significant information was found.
Usually no if…
You applied more than 7 years ago, applied for coverage that was not individually underwritten, or applied with a non-member carrier.
Common surprise
You can still have an MIB file even if you never ended up buying the policy you applied for.
What You May See in Your MIB File
Coded medical information
MIB says its file may contain coded medical or personal underwriting information reported by member companies.
Reporting company details
You may see which member company reported information and when it was reported.
Inquiry history
You may also see which member companies made inquiries about you during the disclosure period.
Translated codes
When MIB sends your file, it says it provides code translations so consumers can understand the file.
How to Request Your MIB Consumer File
| Step | What to Do | Why It Matters |
|---|---|---|
| 1 | Request your own MIB consumer file directly from MIB. | MIB says you can request your file once per year at no charge if one exists. |
| 2 | Verify your identity. | MIB collects identifying information so it can search and release the correct file. |
| 3 | Review the translated file carefully. | You want to understand what was reported, who reported it, and whether it looks accurate. |
| 4 | Dispute anything inaccurate or incomplete. | MIB says consumers can seek correction or modification of inaccurate or incomplete information. |
If an insurer sends you an adverse underwriting letter saying an MIB record influenced the process, MIB also says you may be eligible for an additional free copy.
MIB Report vs Medical Records vs Prescription Checks
MIB file
A coded underwriting-information file used by member carriers for cross-checking and follow-up.
Medical records
Actual records from doctors, hospitals, and providers, which are a different evidence source in underwriting.
Prescription history
Another separate underwriting evidence source insurers may use to check medications and treatment patterns.
This matters because people often assume the MIB file is the same thing as everything the insurer knows about them. It is not.
What Coach B Would Do If MIB Becomes an Issue
Step 1: find the discrepancy
The first job is figuring out what information the carrier thinks does not match and whether it is actually wrong, incomplete, or just misunderstood.
Step 2: pull the file if needed
If the issue seems significant, I would want the consumer file so we know exactly what is sitting there.
Step 3: fix or re-position the case
Sometimes the answer is disputing an error. Sometimes it is explaining the context better. Sometimes it is taking the case to a carrier that fits the file better.
The Bottom Line
The truth about the MIB insurance report is that it is important, but it is not magic and it is not the whole underwriting story.
It is a coded underwriting-information file used by member carriers to cross-check what they are seeing during the application process. If the information is wrong, you have the right to request your file and dispute it. If the information is accurate, the next move is usually understanding the context and positioning the case correctly.
Helpful Related Pages
Applying for a Life Insurance Policy
Best next page if you want the full underwriting and application process explained step by step.
See the Application Process →Can You Retake a Life Insurance Medical Exam?
Best next page if underwriting questions or exam results are part of the issue.
See Exam Troubleshooting →Life Insurance Classifications
Best next page if you want to understand how underwriting findings turn into rate classes.
See Life Insurance Classifications →No Medical Exam Life Insurance
Best next page if you want to compare a path with less traditional underwriting.
See No-Exam Options →Life Insurance for People With Cancer
Best next page if your underwriting concern is tied to a major diagnosis and how carriers interpret it.
See Cancer Coverage Options →High-Risk Jobs and Hobbies Life Insurance
Best next page if lifestyle or occupation flags are part of the underwriting file.
See High-Risk Underwriting →Life Insurance Rates
Best next page if your next question is how underwriting issues can change price.
See Life Insurance Rates →Frequently Asked Questions
What is an MIB insurance report?
It is usually referring to your MIB consumer file, which is a coded underwriting-information file used by member insurers during underwriting.
Is MIB the same as my medical records?
No. MIB is not your full medical record file. It is a coded underwriting-information file used for cross-checking by participating carriers.
Can MIB deny my life insurance application by itself?
MIB says carriers are not enabled to make underwriting decisions based on the MIB consumer file alone without further investigation.
How do I get a copy of my MIB report?
MIB says consumers can request their own MIB consumer file directly from MIB once per year at no charge if a file exists.
Can I dispute wrong information in my MIB file?
Yes. MIB says consumers can seek correction or modification of inaccurate or incomplete information in their consumer file.


