
Life Insurance for Marijuana Users: THC Rules, Rates, and Best Options
Marijuana use does not automatically mean you cannot get life insurance. But it does mean underwriting usually gets more specific about how often you use it, how you use it, why you use it, and what else is going on in your health profile.
That is why this page matters. Most shoppers are not just asking whether marijuana is allowed. They are asking whether they will be treated as a smoker, whether medical marijuana changes the answer, whether no-exam is easier, and whether occasional use gets priced differently than daily use.
The real question is not just whether marijuana and life insurance can work together. The real question is which carrier and underwriting lane give you the best shot at the right classification and the lowest realistic premium.
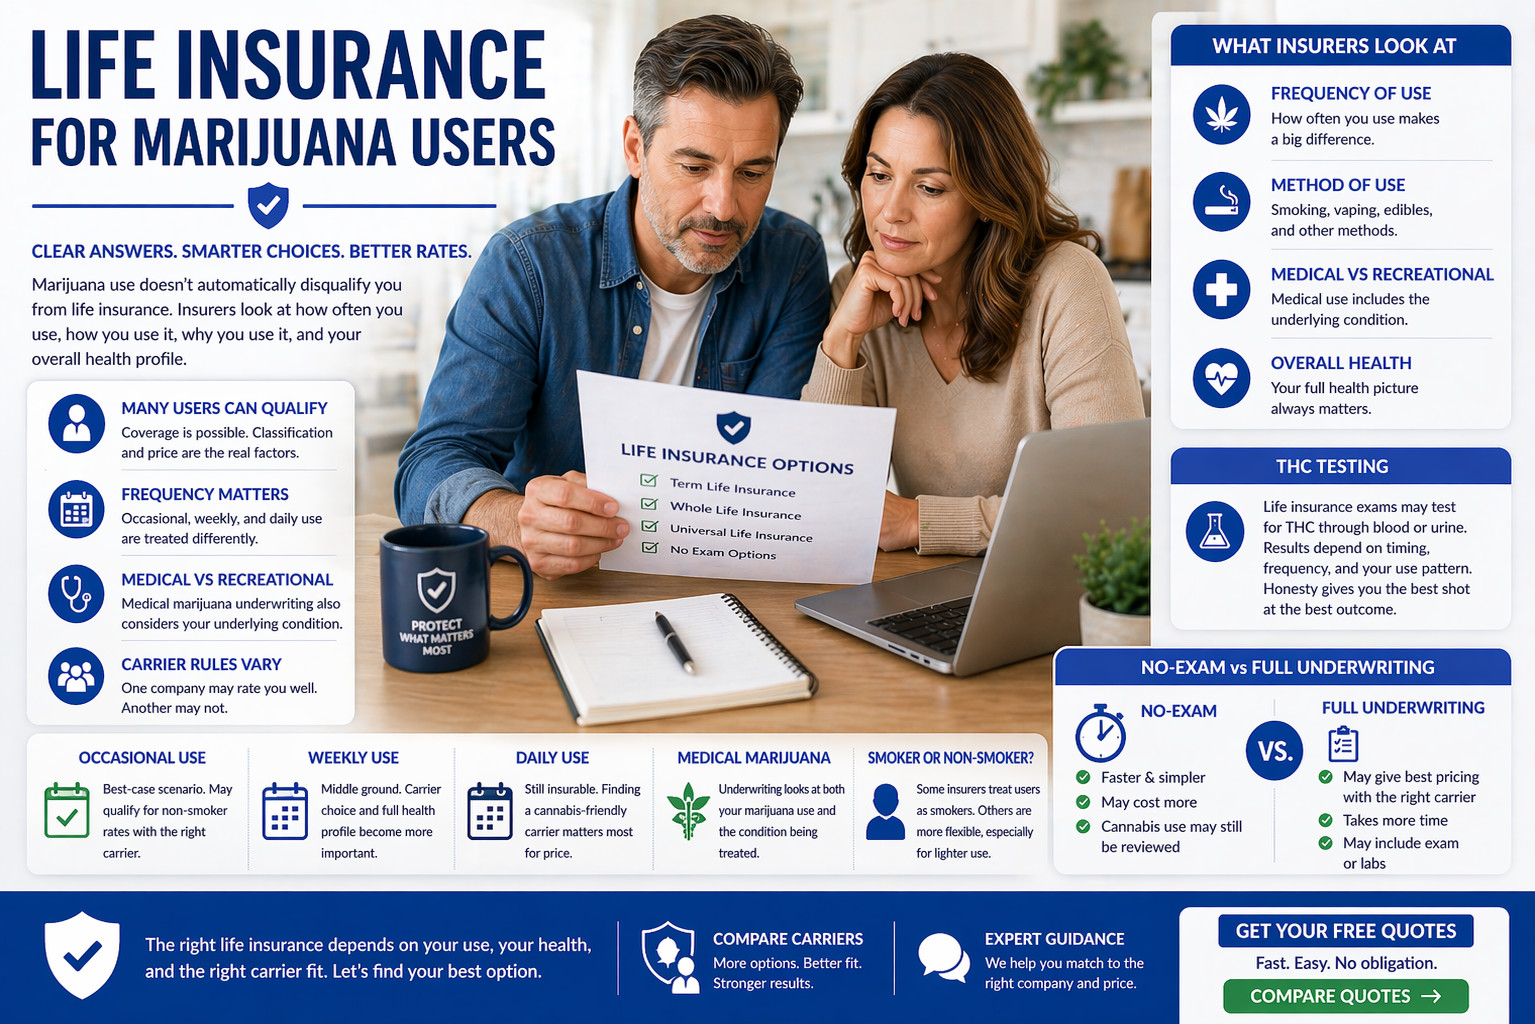
- Many marijuana users can still qualify for life insurance.
- Frequency of use often matters a lot, and occasional users may be treated differently than daily users.
- Medical marijuana can be underwritten differently because the underlying condition matters too.
- Some carriers may treat marijuana users more favorably than others, including in no-exam and traditional underwriting.
- The best strategy is usually comparing carriers instead of assuming every company will view cannabis the same way.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on product fit, underwriting, clarity, and usefulness — not pressure.
Editorial note: The biggest mistake marijuana users make is assuming every carrier treats cannabis the same way. They do not. That is why matching the case to the right company matters so much here.
Can Marijuana Users Get Life Insurance?
Yes, many marijuana users can still get life insurance. The bigger question is not whether coverage is possible. The bigger question is what classification you will get and how much you will pay.
Coverage is often possible
Marijuana use is usually an underwriting factor, not an automatic decline by itself.
Frequency matters
Occasional use and daily use are often treated very differently.
Carrier rules vary
One company may price the case reasonably while another may lean much harder on smoker-style pricing.
Overall profile still matters
Health history, prescriptions, age, tobacco use, and the reason for cannabis use all still matter.
What Insurers Usually Look At
| Factor | Why It Matters | What It Can Affect |
|---|---|---|
| Frequency of use | Occasional, weekly, and daily use are often viewed differently | Rate class and smoker vs non-smoker treatment |
| Method of use | Smoking, vaping, edibles, and other methods may be viewed differently | How the carrier interprets risk and test results |
| Medical vs recreational use | Medical use raises questions about the underlying condition too | Eligibility, pricing, and underwriting follow-up |
| Overall health picture | Cannabis is rarely the only thing being reviewed | Final underwriting class and premium |
Occasional vs Weekly vs Daily Marijuana Use
Occasional use
This is often the best-case marijuana underwriting lane. Some carriers may still consider non-smoker-style pricing depending on the rest of the case.
Regular weekly use
Weekly use often lands in a middle ground where carrier fit matters a lot more and pricing can vary widely.
Daily use
Daily use can still be insurable, but it usually becomes much more important to find a carrier with friendlier cannabis underwriting.
Medical Marijuana and Life Insurance
Why medical marijuana is different
With medical marijuana, underwriting is often looking at two things at once: the marijuana use itself and the condition being treated.
What usually matters more
In many cases, the condition behind the prescription matters as much as or more than the cannabis use itself.
Will Marijuana Make You a Smoker for Life Insurance?
Sometimes yes
Some insurers may classify certain marijuana users into smoker-style pricing lanes.
Sometimes no
Some carriers may be more flexible, especially for infrequent users and otherwise strong health files.
Nicotine still matters separately
If tobacco or nicotine is also involved, that can complicate the pricing picture further.
This is why carrier fit matters
Two insurers can look at the same marijuana-use pattern and come back very differently.
No-Exam vs Fully Underwritten Coverage for Marijuana Users
| Option | Main Advantage | Main Tradeoff |
|---|---|---|
| No-exam life insurance | Faster and simpler process | Can cost more, and marijuana use may still come up through questions or outside data |
| Fully underwritten life insurance | May give the best pricing if the case fits the right carrier well | Takes more time and may involve lab work or a medical exam |
| Instant or accelerated underwriting | Can speed up the process for qualifying applicants | Carrier rules still vary, and not every marijuana profile fits cleanly |
No-exam is not automatically the best marijuana-user strategy. Sometimes full underwriting prices better.
THC Testing and What the Exam May Show
What may be tested
In traditional underwriting, blood and urine testing can still matter. Marijuana use may be discoverable depending on timing, frequency, and the underwriting setup.
Why honesty matters
Trying to game the application usually creates more problems than it solves. Accurate disclosure gives the best chance of putting the case with the right carrier from the start.
How Coach B Would Shop This
Step 1: define the real use pattern
The first job is getting clear about occasional, weekly, or daily use, plus whether the use is recreational or medical.
Step 2: separate cannabis from everything else
Then I would look at the rest of the health picture so marijuana is not being blamed for issues that are really coming from somewhere else.
Step 3: match the case to the right carrier lane
That is where the real value usually shows up — picking the carrier and underwriting path most likely to treat the marijuana use fairly.
The Bottom Line
Marijuana use does not automatically block you from getting life insurance. But it does make carrier choice and underwriting strategy matter a lot more.
The best results usually come from being clear about how often you use marijuana, whether it is medical or recreational, and then comparing carriers that are more likely to treat your case fairly. That is usually a better move than guessing or assuming every company will respond the same way.
Helpful Related Pages
Life Insurance for Smokers
Best next page if your bigger question is smoker vs non-smoker classification and nicotine treatment.
See Smoker Underwriting →No Medical Exam Life Insurance
Best next page if you want the broader no-exam picture after seeing how marijuana fits into it.
Explore No-Exam Options →Instant Issue Life Insurance
Best next page if speed matters and you want to compare faster underwriting lanes.
See Instant Issue Options →Life Insurance Classifications
Best next page if you want to understand how marijuana use can influence rate class and pricing.
See Life Insurance Classifications →Frequently Asked Questions
Can marijuana users get life insurance?
Yes, many marijuana users can still qualify for life insurance. The bigger issue is usually classification and price, not automatic eligibility.
Will marijuana make me a smoker for life insurance?
Sometimes, but not always. Some insurers are stricter than others, which is why comparing carriers matters.
Does medical marijuana affect life insurance differently?
Often yes. With medical marijuana, the underlying condition being treated can matter as much as the cannabis use itself.
Is no-exam life insurance better for marijuana users?
Not always. No-exam can be faster and simpler, but fully underwritten coverage may still price better in some cases.
Do life insurance exams test for THC?
They can. Traditional underwriting may still surface THC depending on timing, testing, and your use pattern.


