
Underwriting Life Insurance Process: How Approval Works, What Underwriters Review, and Why Timing Varies
Underwriting is the part of the life insurance process where the insurer decides how much risk it is taking on and what final offer, if any, it is willing to make.
This page is not about how to fill out the application. It is about what happens after the application is submitted: what data insurers check, why one company may approve faster or more favorably than another, and what can lead to approval, a higher rate, a postponement, or a decline.

Scott Benton (a.k.a. Coach B.)
Author: Scott Benton, Licensed Life Insurance Agent (Coach B. Insurance)
Experience: Serving families since 1992
Disclosure: Coach B. Insurance may be compensated if you purchase through our agency. Recommendations are based on fit, underwriting, and clarity — not pressure.
Editorial note: This page is educational. Underwriting rules, data sources, exam requirements, and approval timing vary by company and state.
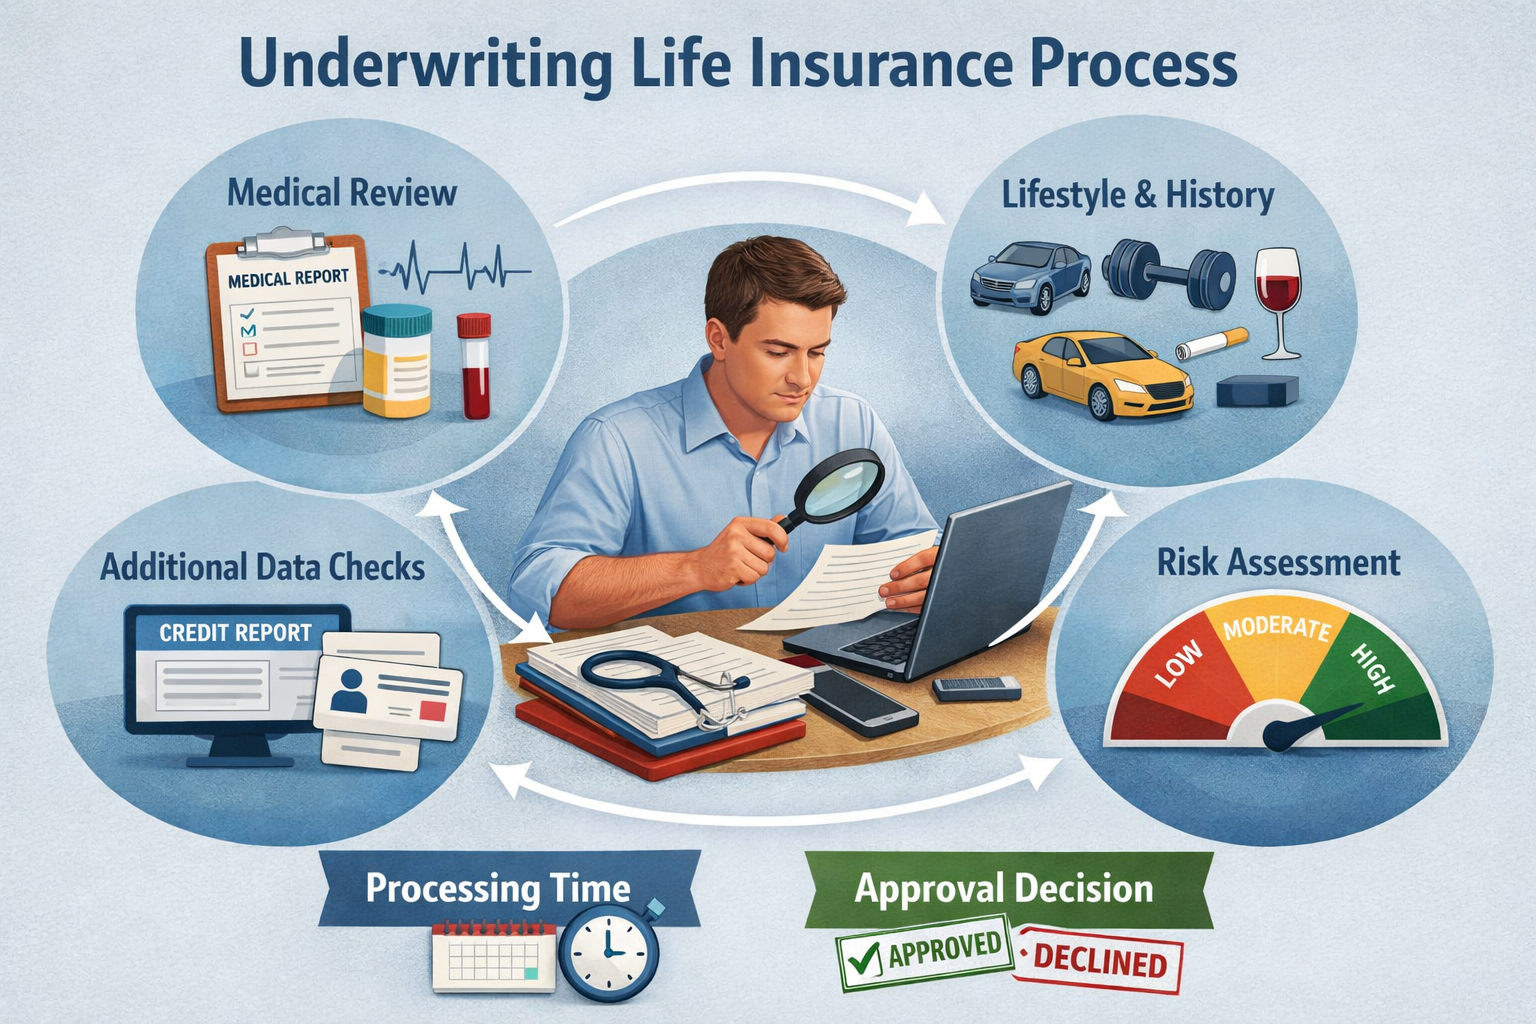
- Health history and treatment stability
- Prescription history
- Nicotine and tobacco use
- Driving record and risk history
- Occupation, hobbies, and lifestyle factors
- Coverage amount requested
What Is Life Insurance Underwriting?
Underwriting is the insurer’s review process after the application is submitted. The company uses it to decide whether to offer coverage, what rate class to assign, and whether the quote changes once real data is reviewed.
This is where the insurer moves from “estimated quote” to “final offer.” For many shoppers, underwriting is the part that feels mysterious, but it is really just the company’s way of measuring risk.
Underwriting decides
- Whether the policy is approved
- What rate class you qualify for
- Whether a medical exam is needed
- Whether extra records are required
- Whether the offer changes before issue
When Underwriting Starts in the Process
Underwriting begins after the application is submitted. That is the main difference between this page and the application page.
The application page is about what you fill out and what you need to start. This page is about what the insurer does after that information is in hand.
Start here first if needed
If you want the step-by-step application overview instead of the insurer review phase, go here:
Life Insurance Application →What Do Underwriters Actually Look At?
Medical history
Diagnoses, treatment, follow-up care, severity, and stability often matter more than the diagnosis label alone.
Prescription history
Medication patterns can help confirm treatment history and raise questions when the application and pharmacy record do not match.
Tobacco and nicotine use
Nicotine use can change rate class quickly and can also affect whether a no-exam path is realistic.
Height and weight
Build charts differ by carrier, which is one reason two companies can view the same case differently.
Driving record
DUIs, repeated violations, and serious accidents can affect rate class or carrier fit.
Occupation and hobbies
High-risk work or dangerous hobbies can change approval or pricing even when medical history is clean.
Common Data Sources Used in Underwriting
Application answers
Your application is the starting point. Accuracy matters because it gets checked against other sources.
MIB report
The MIB is a verification tool insurers may use to compare current disclosures with coded prior application data.
Prescription database
Prescription history helps underwriters confirm treatment patterns and identify risk indicators.
Medical records
For some cases, the insurer may request an attending physician statement or other records.
For the MIB specifically, use The Truth About the MIB Insurance Report →
Traditional Underwriting vs Accelerated Underwriting
Traditional underwriting
- More likely to use an exam for some cases
- May request medical records
- Often slower, but sometimes more flexible
- Can work better for certain complex cases
Accelerated underwriting
- Often skips the medical exam
- Relies more on digital data sources
- Can move much faster
- Works best for cleaner, lower-risk profiles
If exam avoidance is your main goal, use No Medical Exam Life Insurance →
Want a Better Shot at the Right Offer?
The biggest underwriting mistake is assuming every company will look at your case the same way. Compare carriers first when health history, prescriptions, or prior issues are involved.
How Long Does Underwriting Take?
Fast digital cases
Some cases move quickly when the profile is clean and the carrier can make a decision from digital data.
No-exam cases
These may be faster than traditional underwriting, but not every no-exam case is instant.
Record-heavy cases
If doctor records are needed, timing often depends more on the provider response than the insurer itself.
Complex health profiles
More nuance usually means more manual review, which can stretch underwriting out.
Possible Underwriting Outcomes
Approved as applied
The insurer issues the policy substantially as expected.
Approved at a different class
The policy is still approved, but the final rate class is lower than the original quote assumed.
Postponed
The company may want more time, more records, or more medical stability before making a final decision.
Declined
The insurer does not offer coverage under its current rules, though another carrier may still be possible.
For classification outcomes, use Life Insurance Classifications → and for decline-focused guidance, use What Makes You Uninsurable for Life Insurance →
Why One Company May Approve You More Favorably Than Another
This is one of the biggest underwriting truths in life insurance: companies do not all read risk the same way.
One carrier may treat a condition as manageable and offer standard pricing. Another may table-rate it. Another may postpone the case. That is why carrier fit often matters more than people expect.
Carrier fit matters when you have
- Diabetes
- Sleep apnea
- Depression or anxiety history
- High blood pressure
- Prior decline or postponement
What Can Slow Underwriting Down?
Incomplete answers
If the application leaves gaps, the insurer may need follow-up before it can keep moving.
Medical record delays
Doctors’ offices and hospitals are often the slowest part of the timeline, not the insurance company.
Mismatch across data sources
If application answers do not line up with prescription or MIB data, underwriting can slow down fast.
How to Improve Your Underwriting Outcome
Be accurate
Consistency across the application, prescription history, and records matters more than sounding perfect.
Use the right carrier
Carrier fit can change approval odds and pricing more than many shoppers realize.
Apply at the right time
Sometimes waiting for more treatment stability or better control can improve the final offer.
Pick the right path
Traditional, no-exam, accelerated, and guaranteed issue are not interchangeable underwriting paths.
Helpful Next Pages
Life Insurance Application
Use this if you want the step-by-step application overview rather than the insurer review phase.
Open Application Guide →MIB Insurance Report
Use this if you want to understand one specific verification tool underwriters may check.
Open MIB Guide →Life Insurance Classifications
Use this if you want to understand rate classes, table ratings, and what final underwriting outcomes can mean.
Open Classifications Guide →Frequently Asked Questions About the Underwriting Life Insurance Process
What is underwriting in life insurance?
Underwriting is the insurer’s review process after the application is submitted. It is how the company decides approval, pricing, and final rate class.
How long does life insurance underwriting take?
It varies. Cleaner digital cases can move faster, while cases that require records, manual review, or extra verification can take longer.
What do life insurance underwriters look at?
They often review health history, prescriptions, nicotine use, driving record, occupation, hobbies, and the amount of coverage requested.
Can two life insurance companies underwrite me differently?
Yes. Carrier rules differ, which is why one company may offer better pricing or a better classification than another.
Does no-exam life insurance still use underwriting?
Yes. No-exam usually changes the underwriting method, not the fact that risk is still being evaluated.
Understand the Review Process Before You Assume the Quote Is Final
The more you understand underwriting, the easier it becomes to compare carriers, set realistic expectations, and avoid surprises between quote and approval.


